Republic Republic Republic
  • Log in
Open account
Oops! We couldn’t find any results...
Can’t find a deal? Try advanced search.
Is something missing? Add your suggestion here.
Live deals Investment opportunities Trading Buy and sell Republic Note Own a piece of Republic's upside
Republic Ventures Opportunities for accredited investors
Republic Capital Multi-stage venture firm
Wallet Manage your digital assets Mobile app Available on iOS or Android Learning center Explore investor resources FAQ Get your questions answered
Capital fundraising Raise on Republic Tokenized assets Design, launch, manage tokenized assets Sharedrops Gift equity as a reward Founder Academy A complete guide to raising funds
Advisory Access veteran web3 advisors Infrastructure Stake your digital assets Tokenization Deploy your assets on-chain
Republic Capital In-house Venture Capital fund Broker dealer Regulated capital services
Republic Republic Republic
Oops! We couldn’t find any results...
Can’t find a deal? Try advanced search.
Is something missing? Add your suggestion here.
  • US

  • Log in
  • Open account
All investors
Live deals Investment opportunities Trading Buy and sell
Republic Note Own a piece of Republic's upside
Accredited only
Republic Ventures Opportunities for accredited investors
Institutional
Republic Capital Multi-stage venture firm
More
Wallet Manage your digital assets Mobile app Available on iOS or Android Learning center Explore investor resources FAQ Get your questions answered
Spotlight deal
Miso Robotics
Miso Robotics
The Flippy Fry Station robot and a new AI operating system for modern restaurants and hospitality
Growth capital solutions
Capital fundraising Raise on Republic Tokenized assets Design, launch, manage tokenized assets Sharedrops Gift equity as a reward Founder Academy A complete guide to raising funds
Web3 services
Advisory Access veteran web3 advisors Infrastructure Stake your digital assets
Tokenization Deploy your assets on-chain
Institutional services
Republic Capital In-house Venture Capital fund
Broker dealer Regulated capital services
Logo of TRADEFUNDED LLC

TRADEFUNDED LLC · Prop Trading Reinvented Into A Sustainable Growth Model

B2C Fintech AI & Machine Learning Blockchain Security
Facebook Telegram Twitter LinkedIn
Featured image of TRADEFUNDED LLC
$3,750
5% raised of $75K min
3
Investors
87 days
Left to invest
Invest in TRADEFUNDED LLC
$350 minimum investment · Deal terms
Pitch Discussion 5 Updates Reviews 1
Invest Invest in TRADEFUNDED LLC
Facebook Telegram Twitter LinkedIn
Problem Solution Certification Examinations Platform and Infrastructure Market Biz. model What Comes Next Benefits Leadership Community Ownership Summary
About Team FAQ Risks Discussion

Documents

Republic (OpenDeal Portal LLC, CRD #283874) is hosting this Reg CF securities offering by TradeFunded LLC. View the official SEC filing and all updates:
Official SEC Logo Form C SEC.gov
Company documents
Subscription Agreement TradeFunded LLC - Form C.pdf
Loading

Hear from some of the 3 investors in TRADEFUNDED LLC


Show more

Highlights


Join the team building TRADEFUNDED, a new kind of futures firm where the traders who prove themselves become owners alongside you. As an investor, you own shares of the company itself, the same company its certified traders hold a stake in. This is your chance to own a piece of the firm this industry should have built years ago.

  • Retail prop founders, former leaders of a top firm
  • Direct-to-Live: No mandatory simulated stage after qualifying
  • Three revenue lines: exams, licensing, and trading P&L
  • Tachyon: Proprietary, in-house, licensable trading tech
  • We run exams; TRADEFUNDED CAPITAL backs those who pass

Problem


Prop trading is a simple idea.

A firm puts its own capital behind skilled traders and shares the results. To find those traders, firms sell evaluations.

It is a genuinely good idea but the industry deserves a better process.
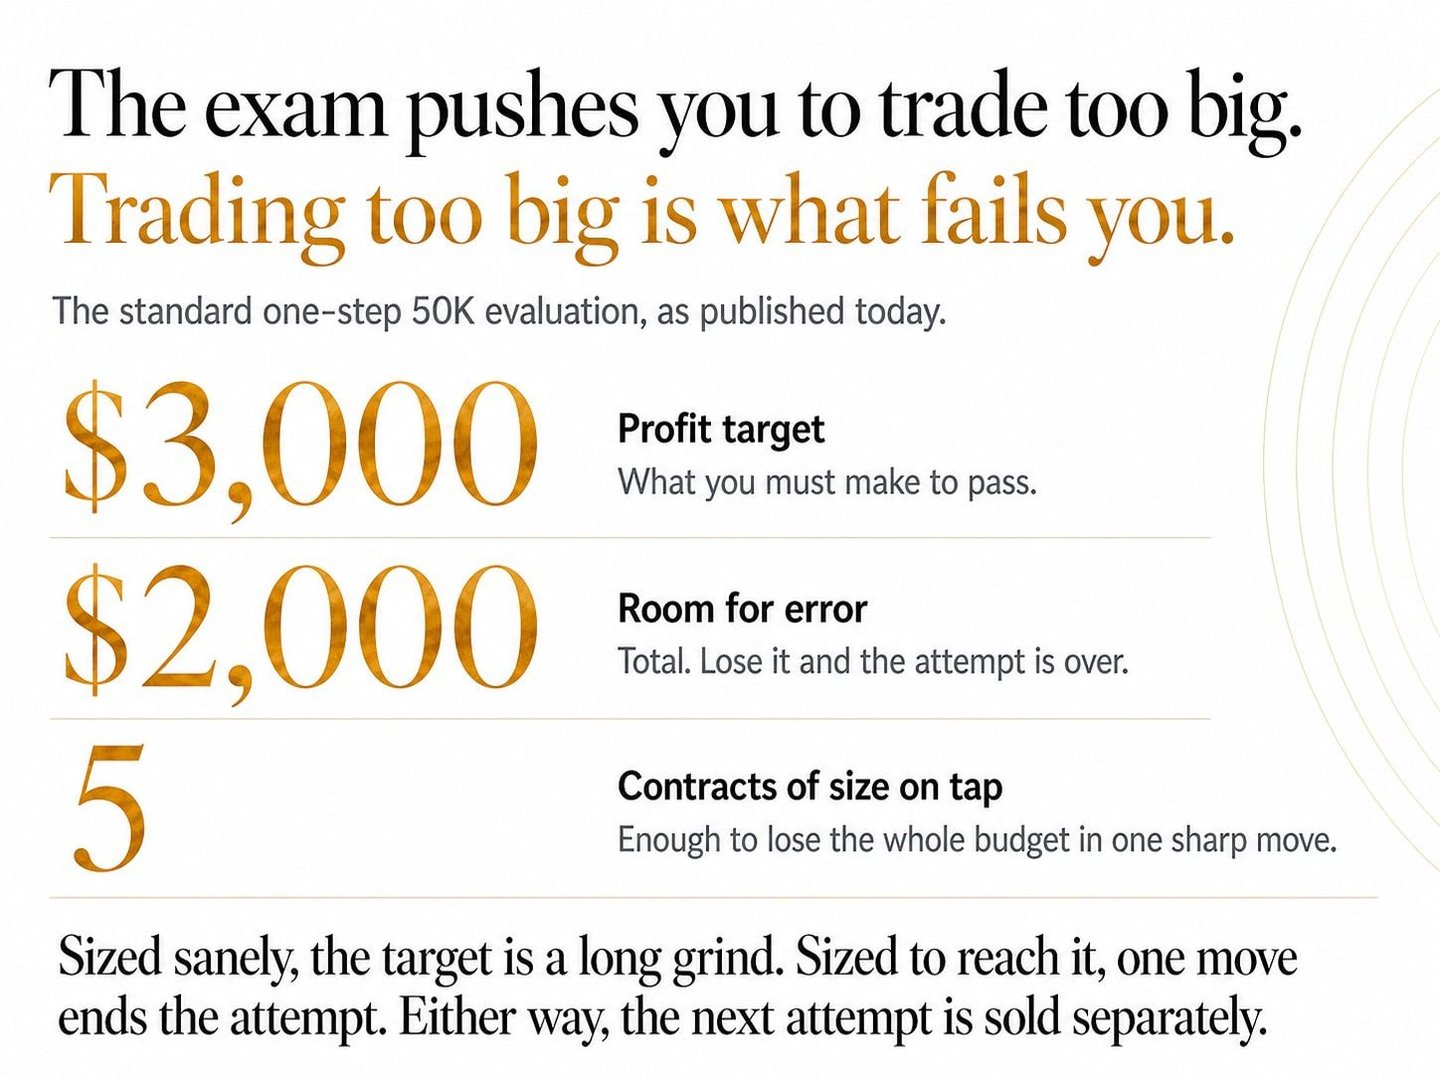


Why would a firm design its exam that way? 

Because of where the money goes when someone wins.
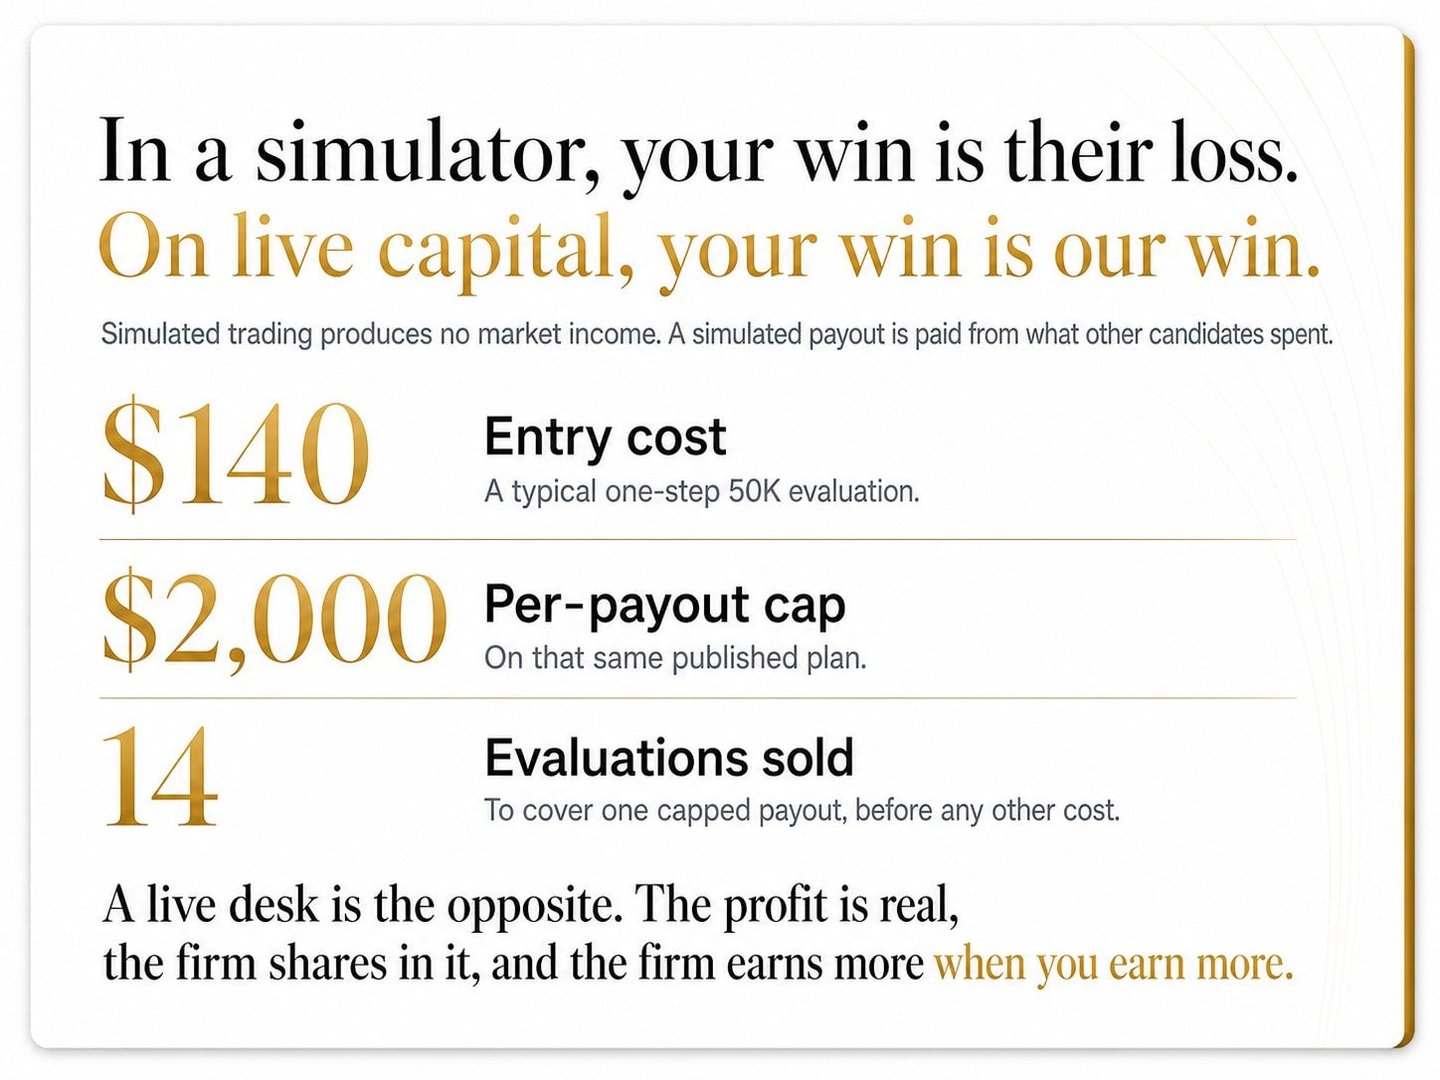


Passing is not the finish line either.

At most firms, a second set of rules begins after you pay: rules about how you must trade once funded, and what you must clear before you are actually paid. Few people ever see that list written down in one place.
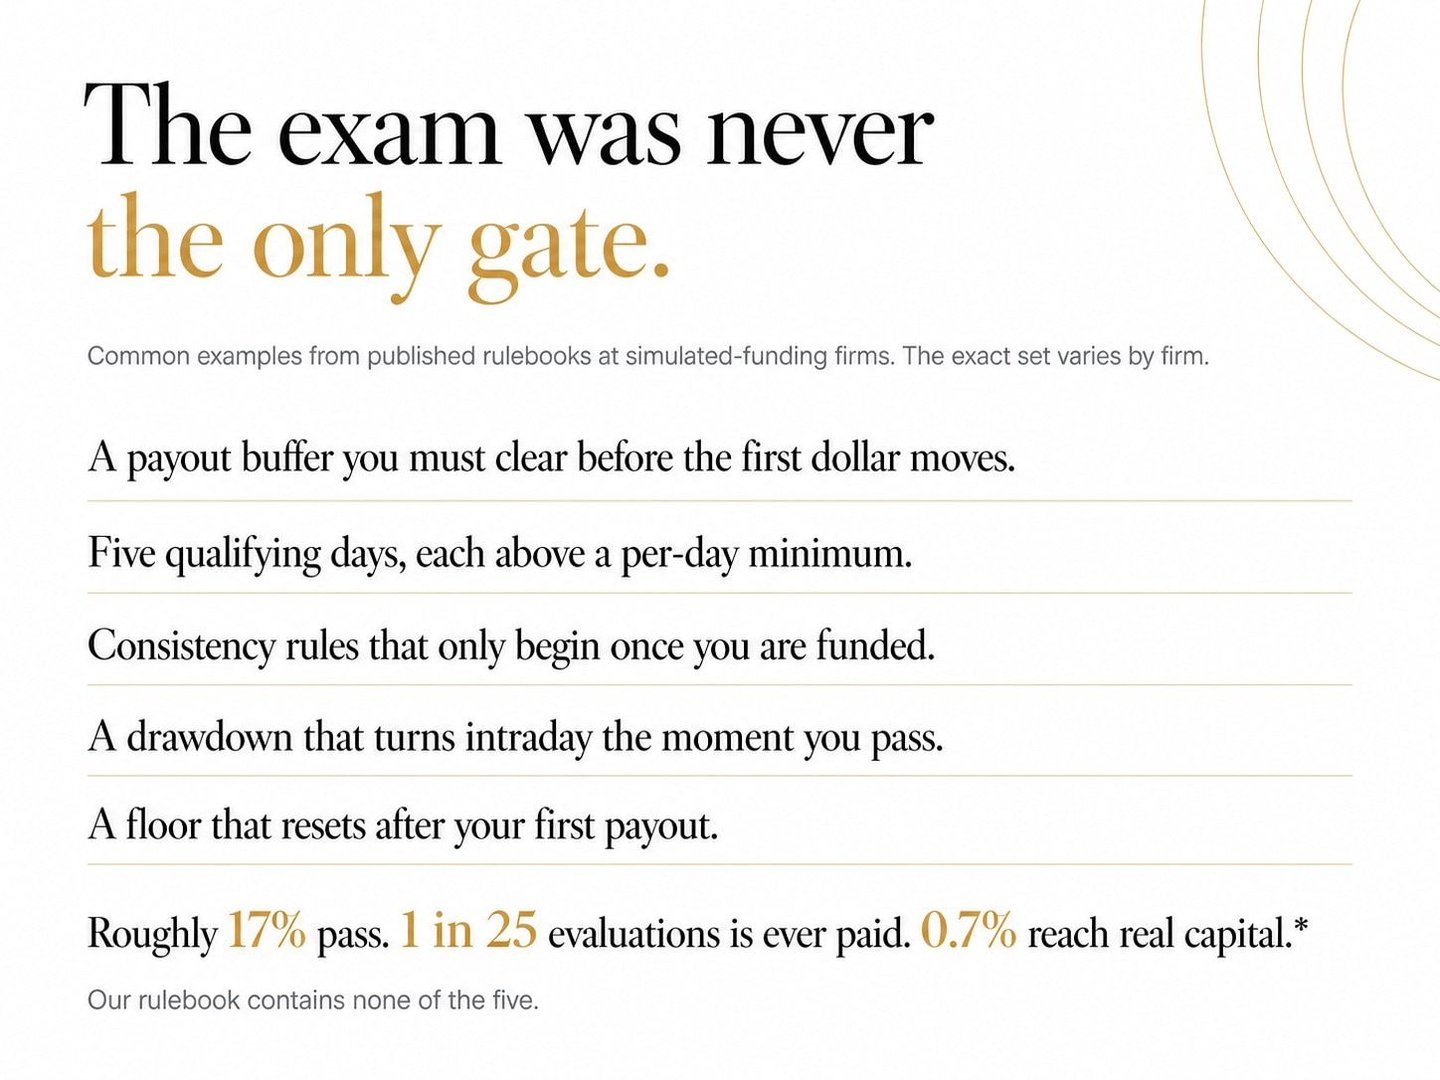


* Pass rates are per evaluation purchased, taken from the published performance statistics of the firms that disclose them, 2025–26. "1 in 25" and "0.7%" are derived from those same disclosures: the published pass rate multiplied by the same firm's published funded-to-payout and funded-to-live rates. Sources and arithmetic available on request.

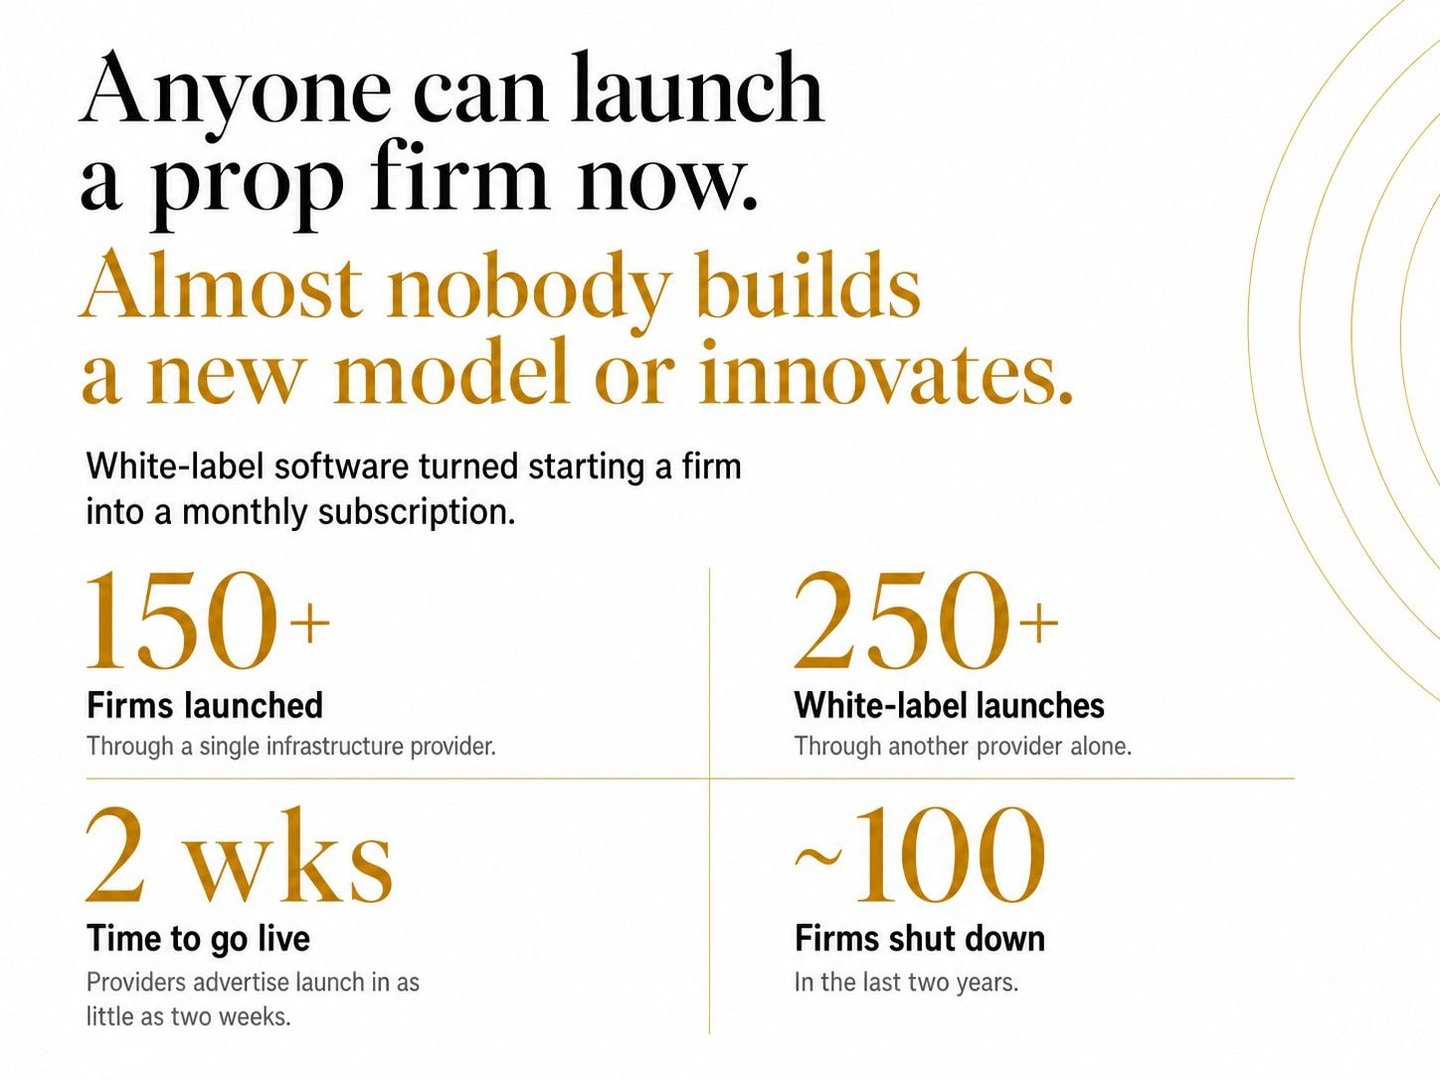
The barrier to entry collapsed.

White-label software turned launching a firm into a monthly subscription, so the market filled with brands running the same playbook on rented infrastructure.

Solution


A firm that earns when qualified traders perform

We went back to first principles and rebuilt the idea around one belief: a firm should build its future on developing successful live traders, not on subscriptions, resets and repeated failure.
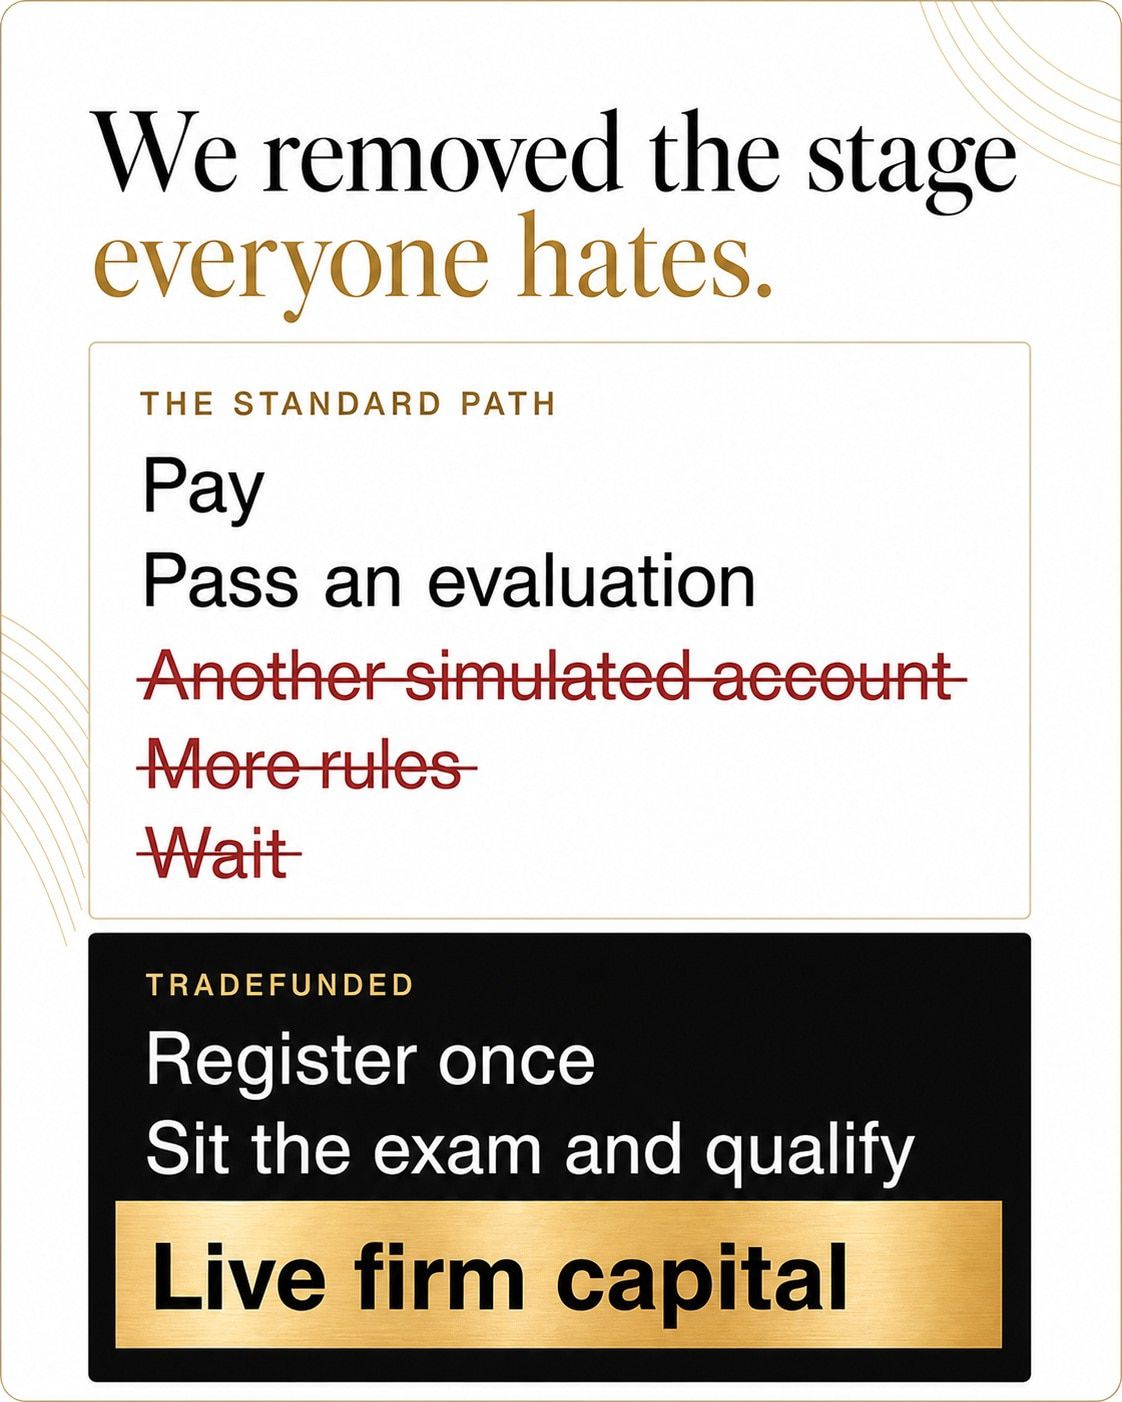


Here is the stage everyone hates. You pass the evaluation, and the reward is another simulated account. More rules, more waiting, a live market somewhere on the horizon. 

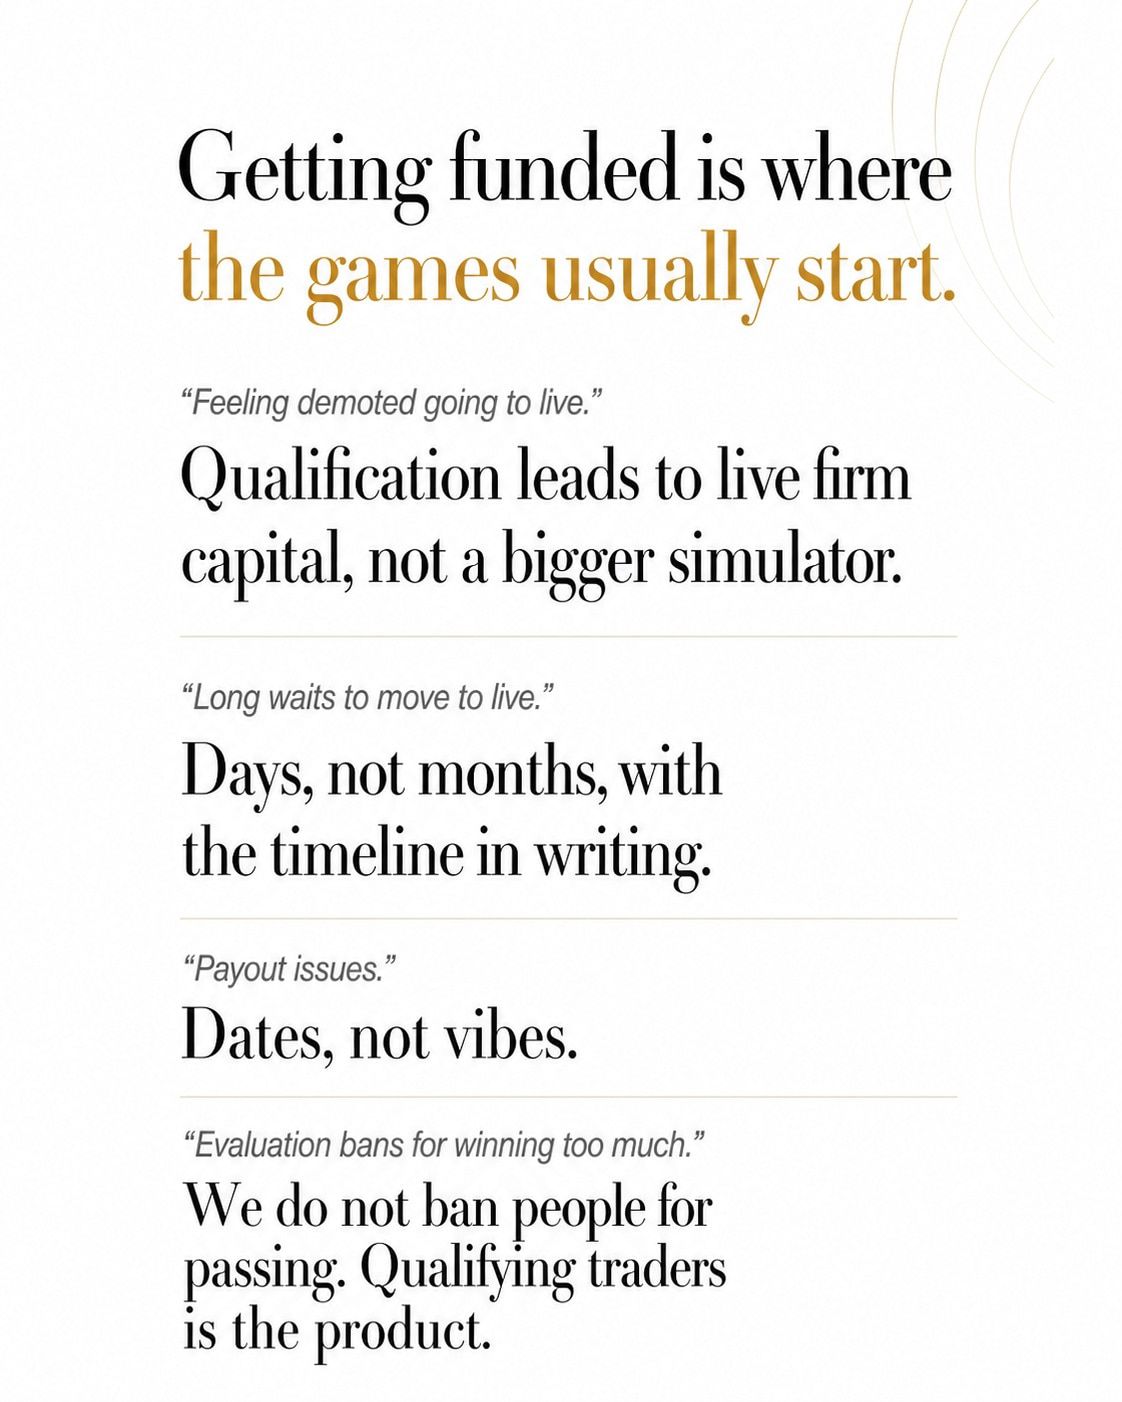
In our model there is no mandatory simulated stage in between. You qualify against published criteria, and the next step is consideration for live firm capital. 

To be clear about who you are joining: qualified traders trade at TRADEFUNDED CAPITAL, our proprietary trading firm. TRADEFUNDED runs the examinations; TRADEFUNDED CAPITAL runs the desks.
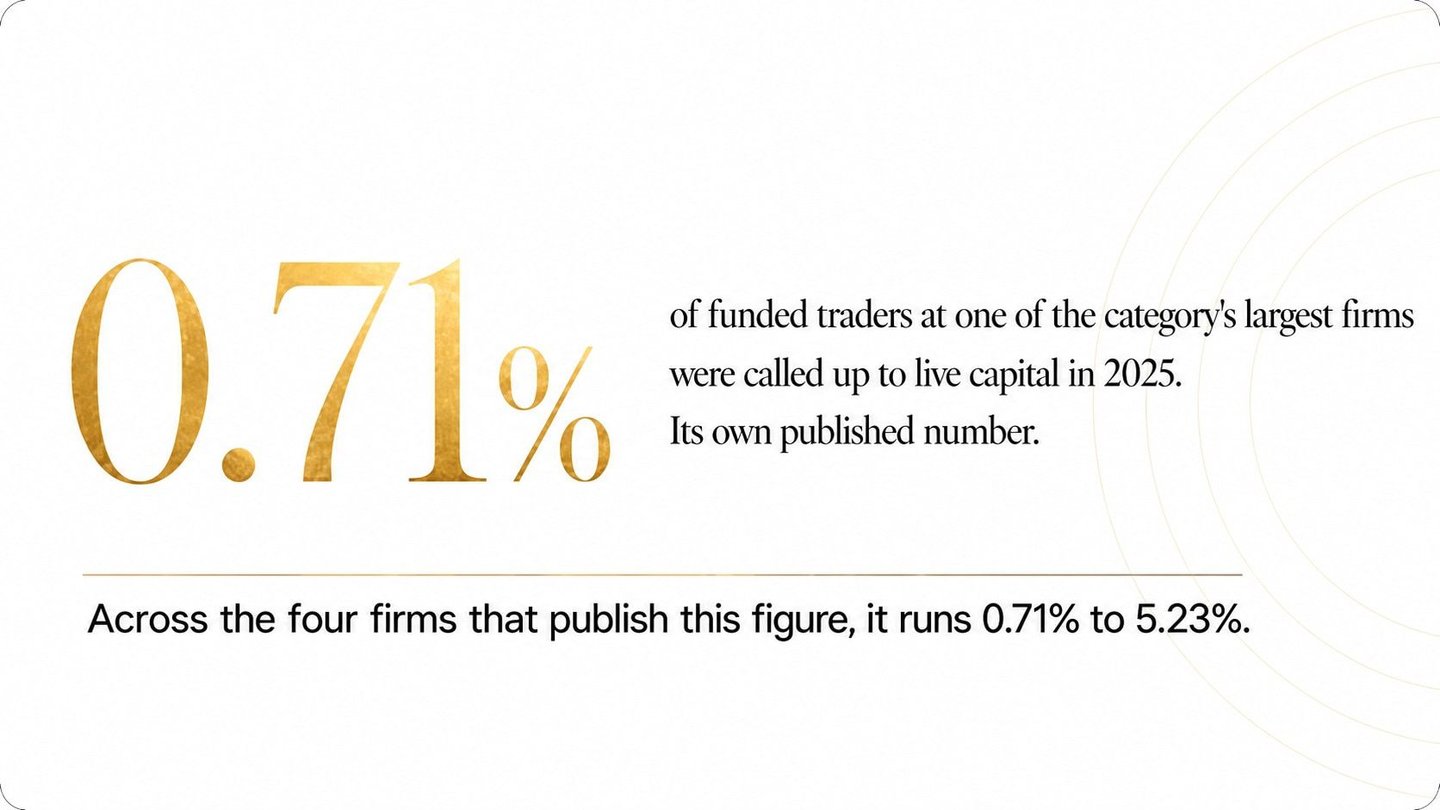


We watched the first generation of this category get built. We think the second belongs to whoever fixes it.

Certification Examinations


Two published standards and a format that treats candidates like professionals.


Our evaluations are structured like professional examinations.

Timed, standardized, and judged on what actually matters. 

Qualify, and it should mean something.

Both standards are published in full before launch, with the whole rulebook alongside them.
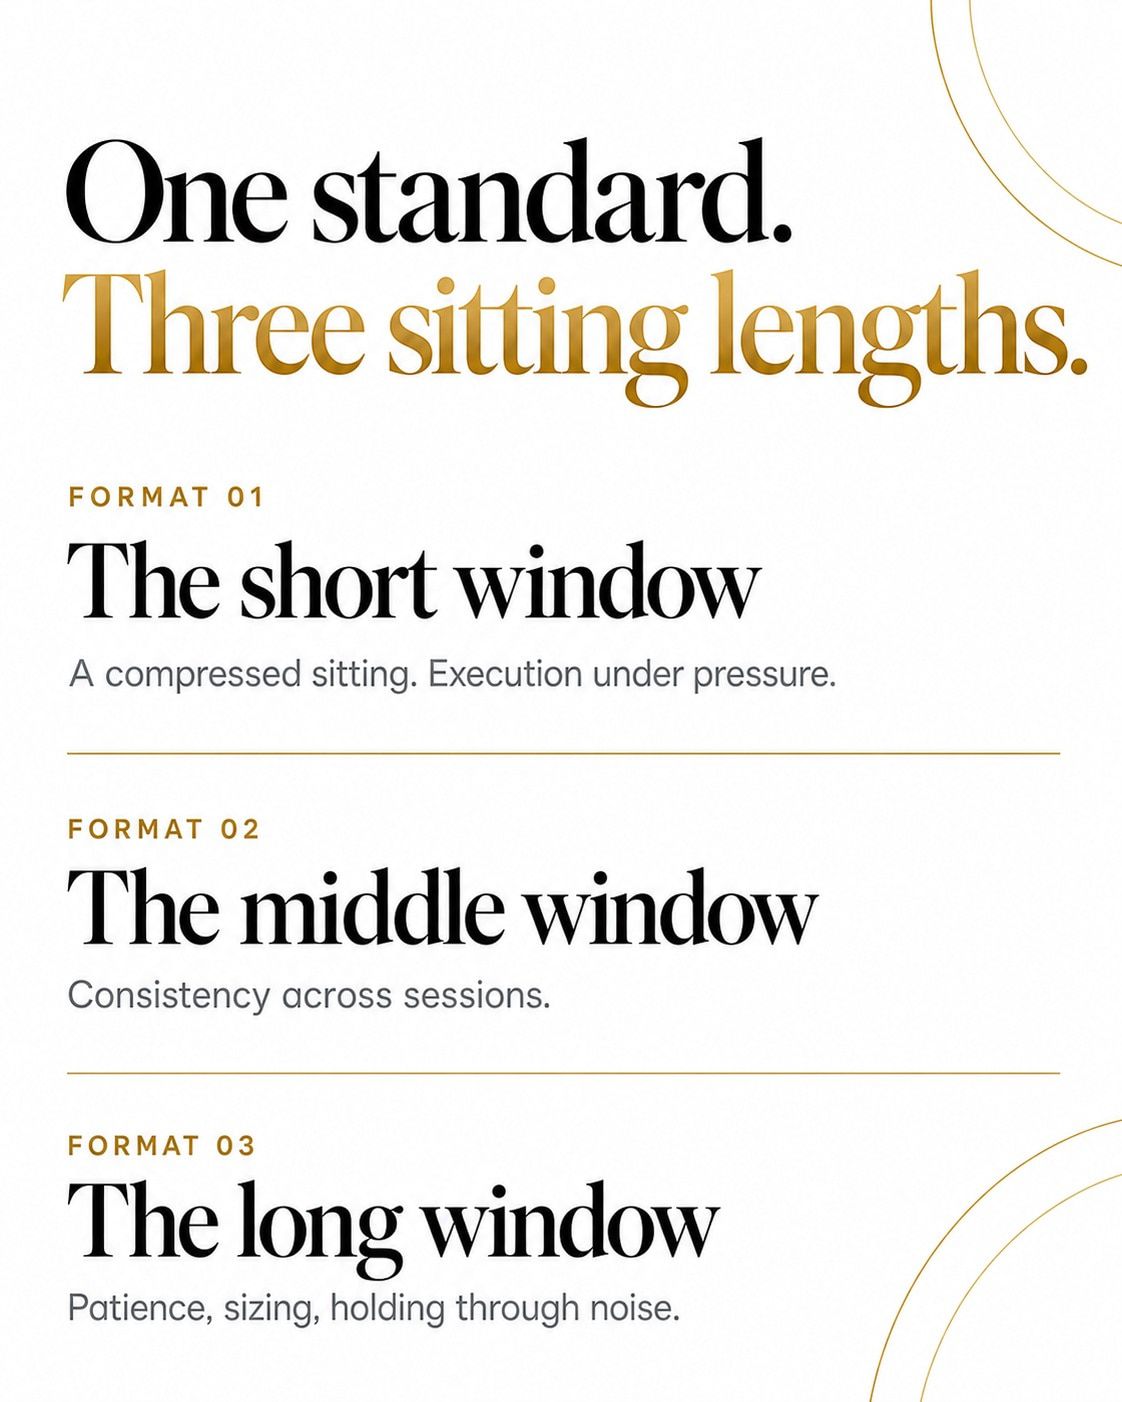


The formats differ only in length. What never changes is what the account is: as close to a real account as we can make it.


Before we wrote a single rule we read what traders say about this industry, in their own words, and built against the list.
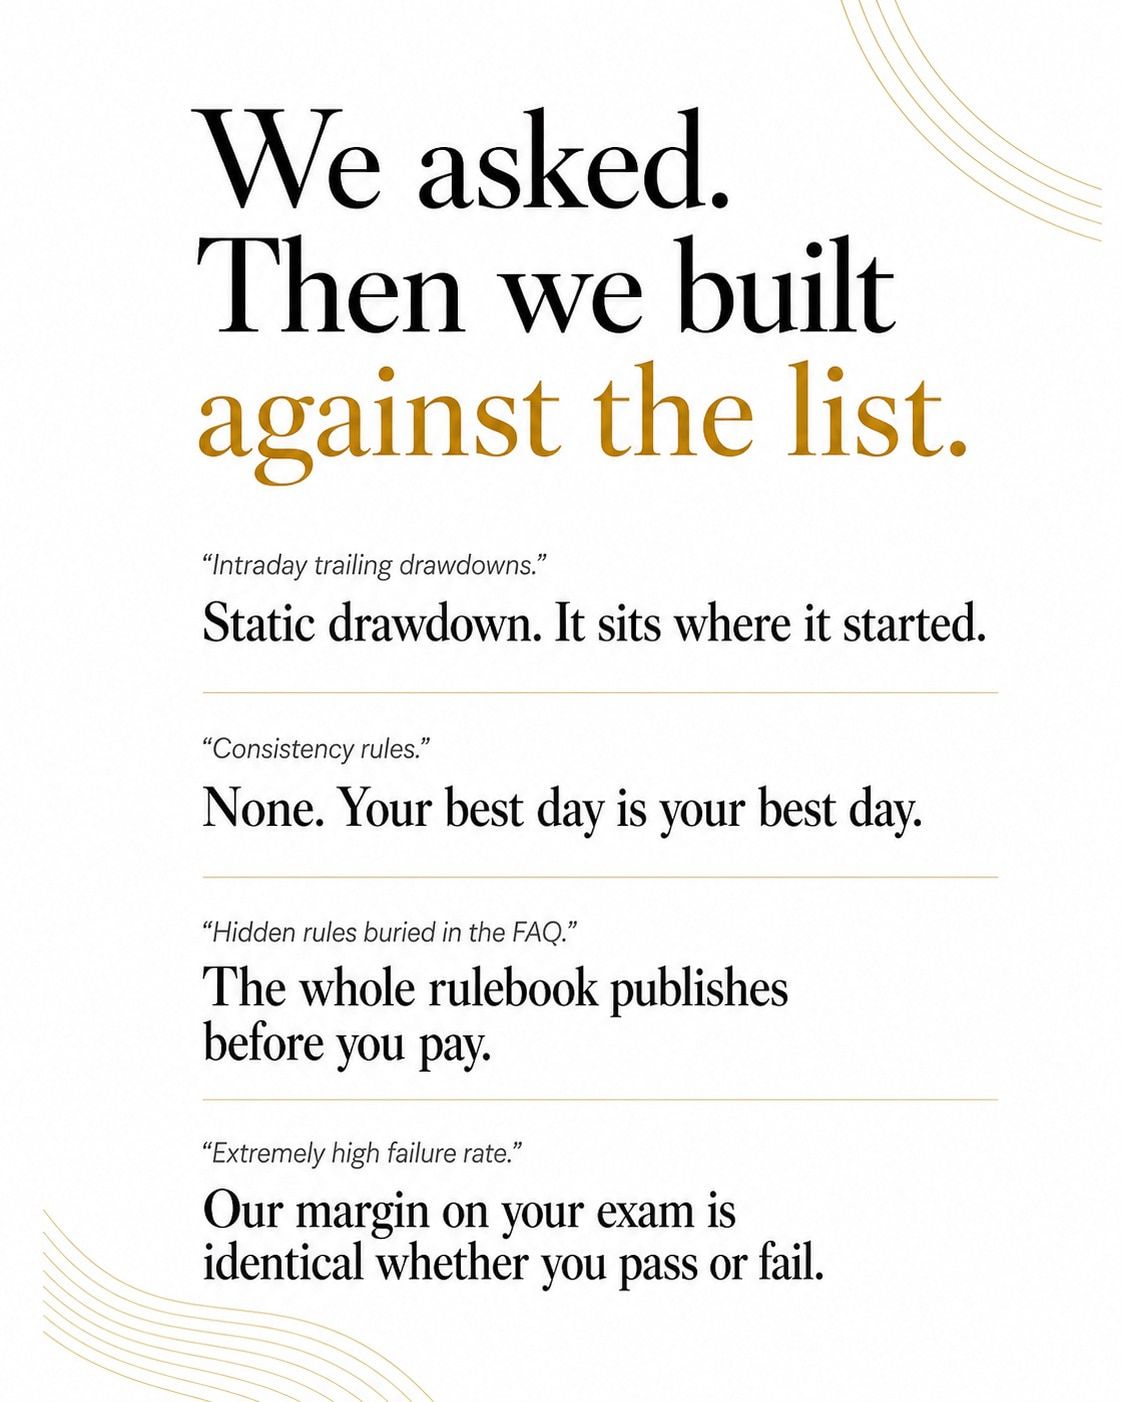


That was the exam. The list gets longer after it.


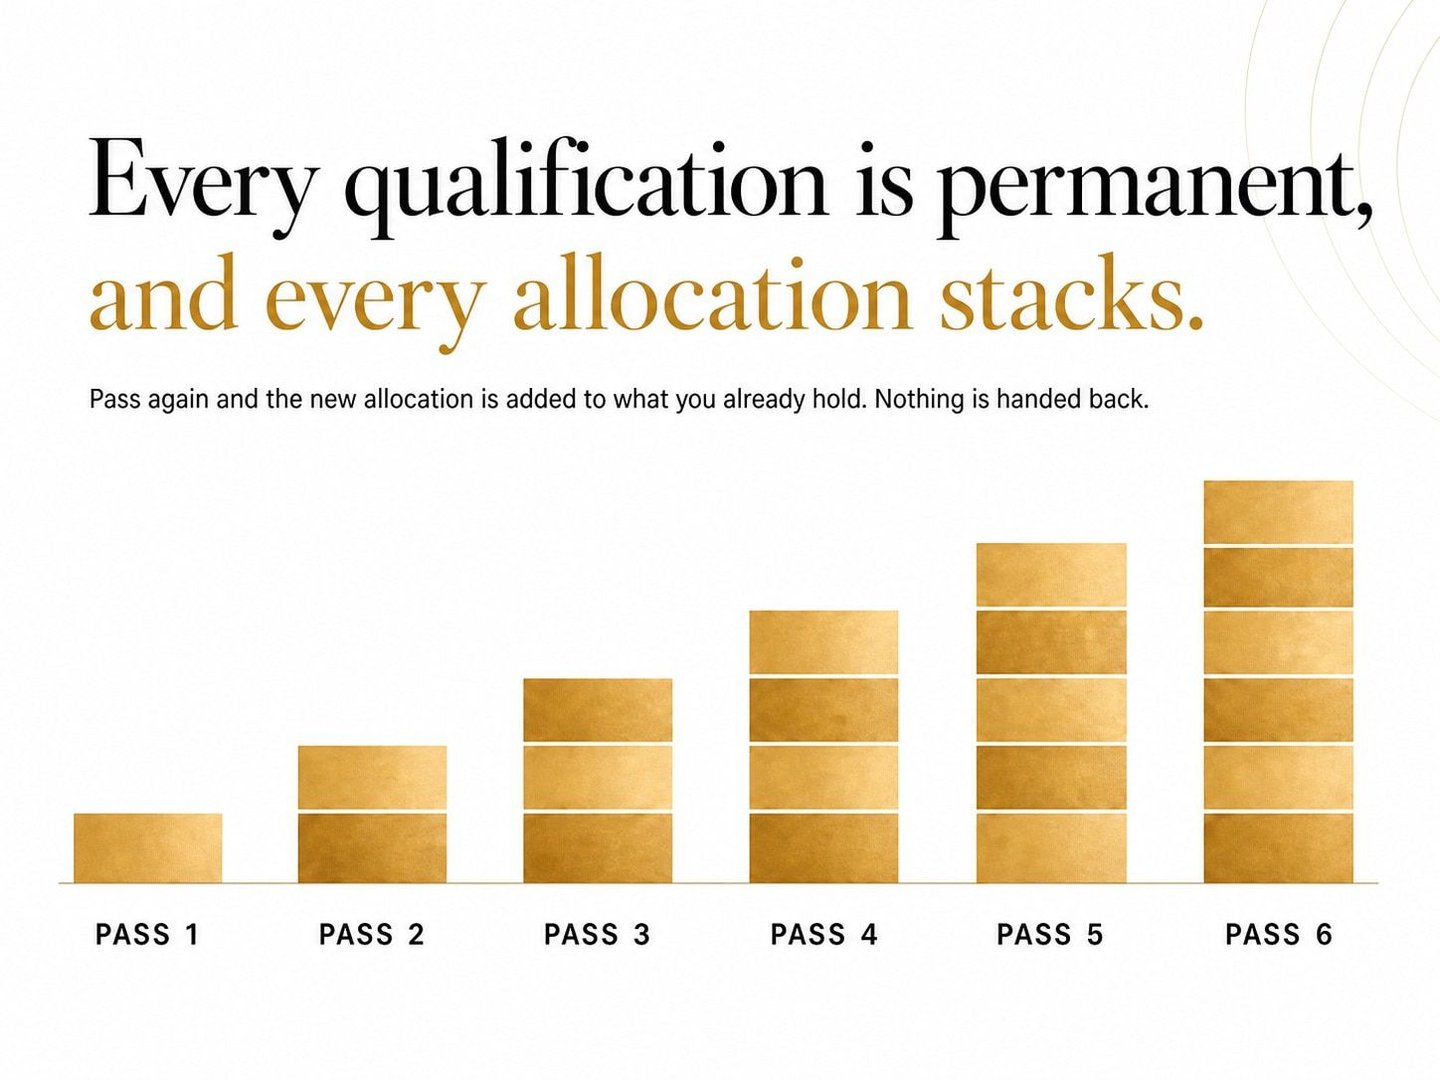
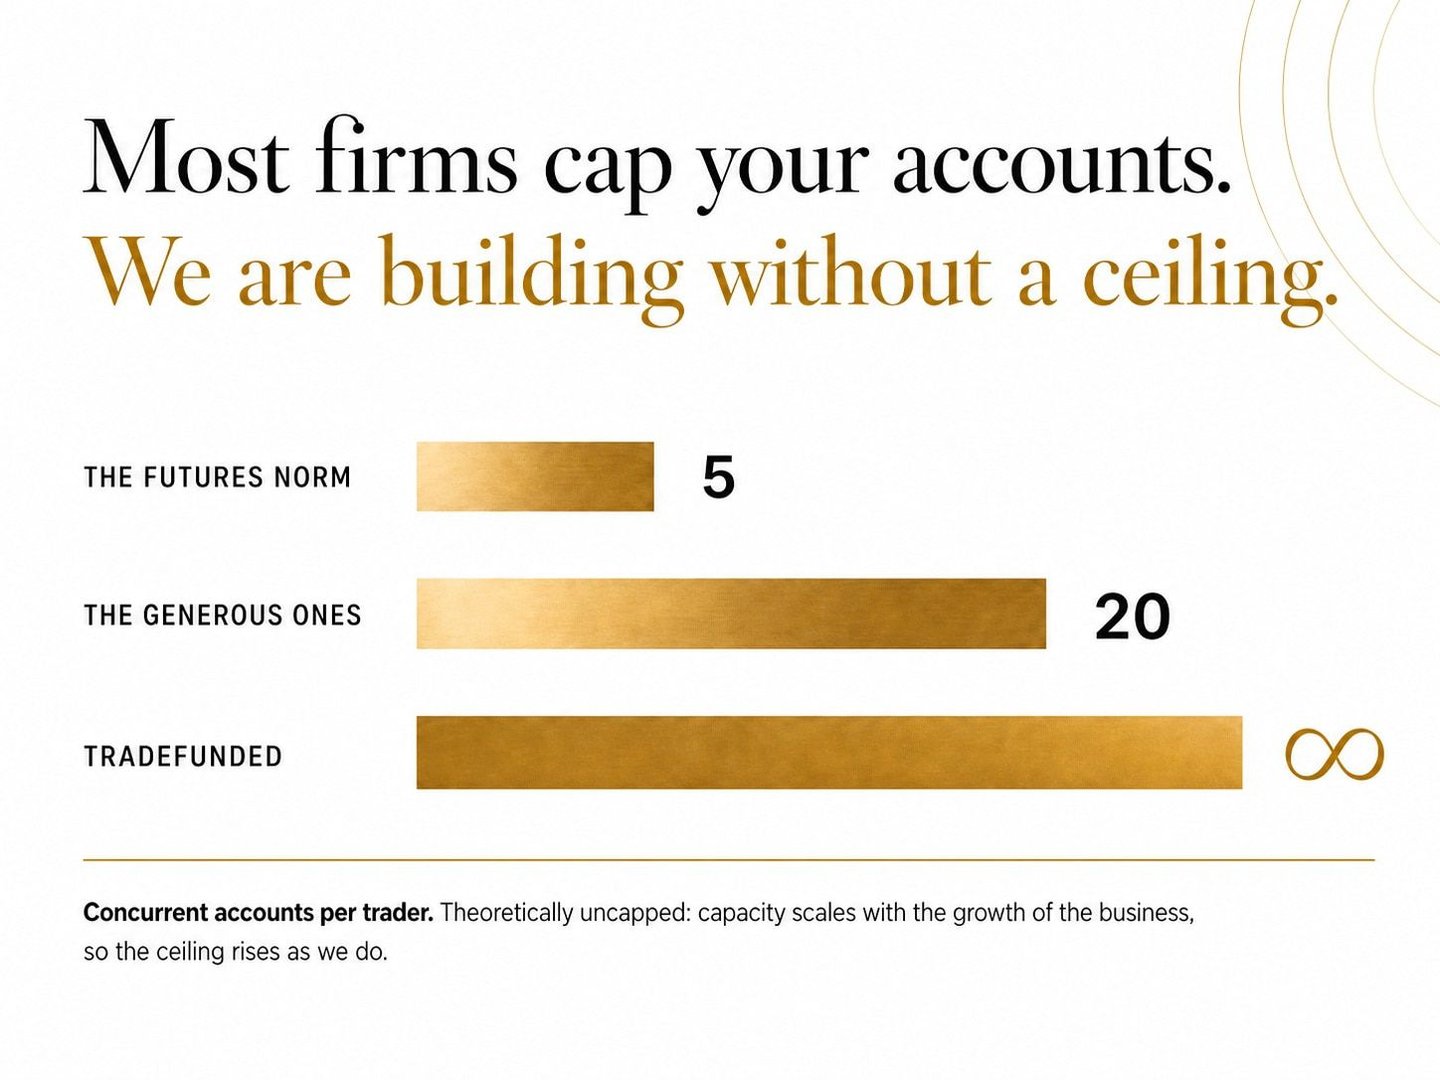
Each pass adds its allocation on top of what you already hold. 

That only works if the number of accounts you can hold keeps growing too.

Platform and Infrastructure


We watched firms lose their entire trading stack when the vendor decided it wanted the business for itself. 

Renting the thing your company runs on is a risk we were not willing to carry, so Tachyon is ours.

For the parts we cannot own, we chose carefully. Clearing and order routing sit with TRADEFUNDED CAPITAL, the entity that trades.
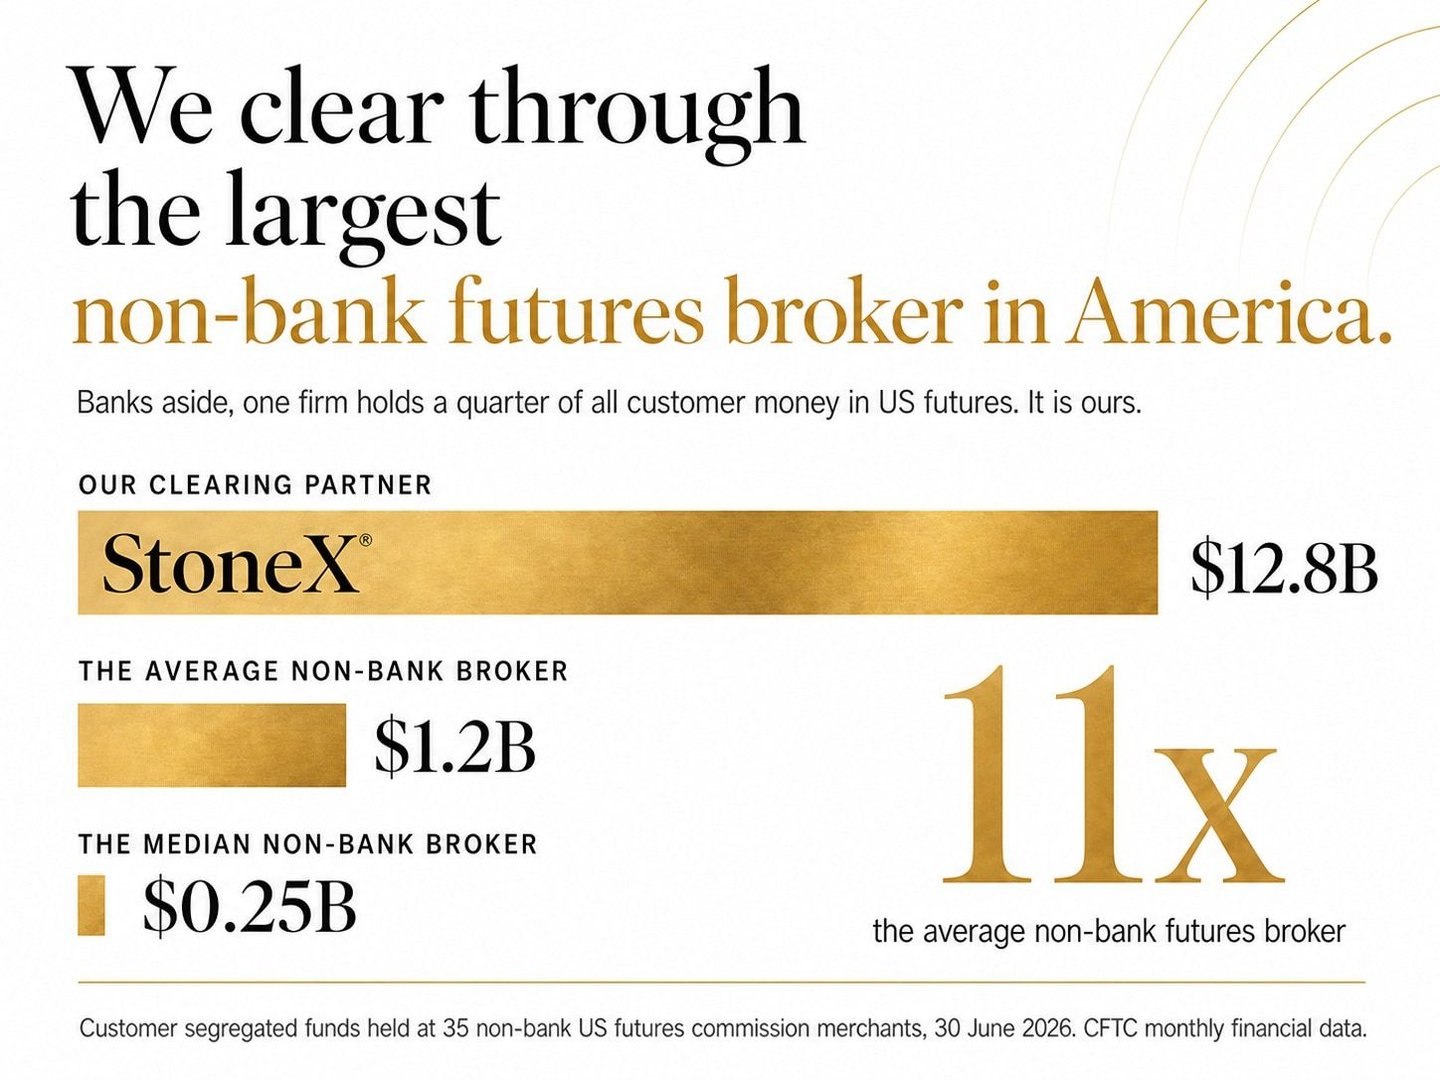


And for the feed itself, we went to the people who carry a large share of the futures market every day.

Market
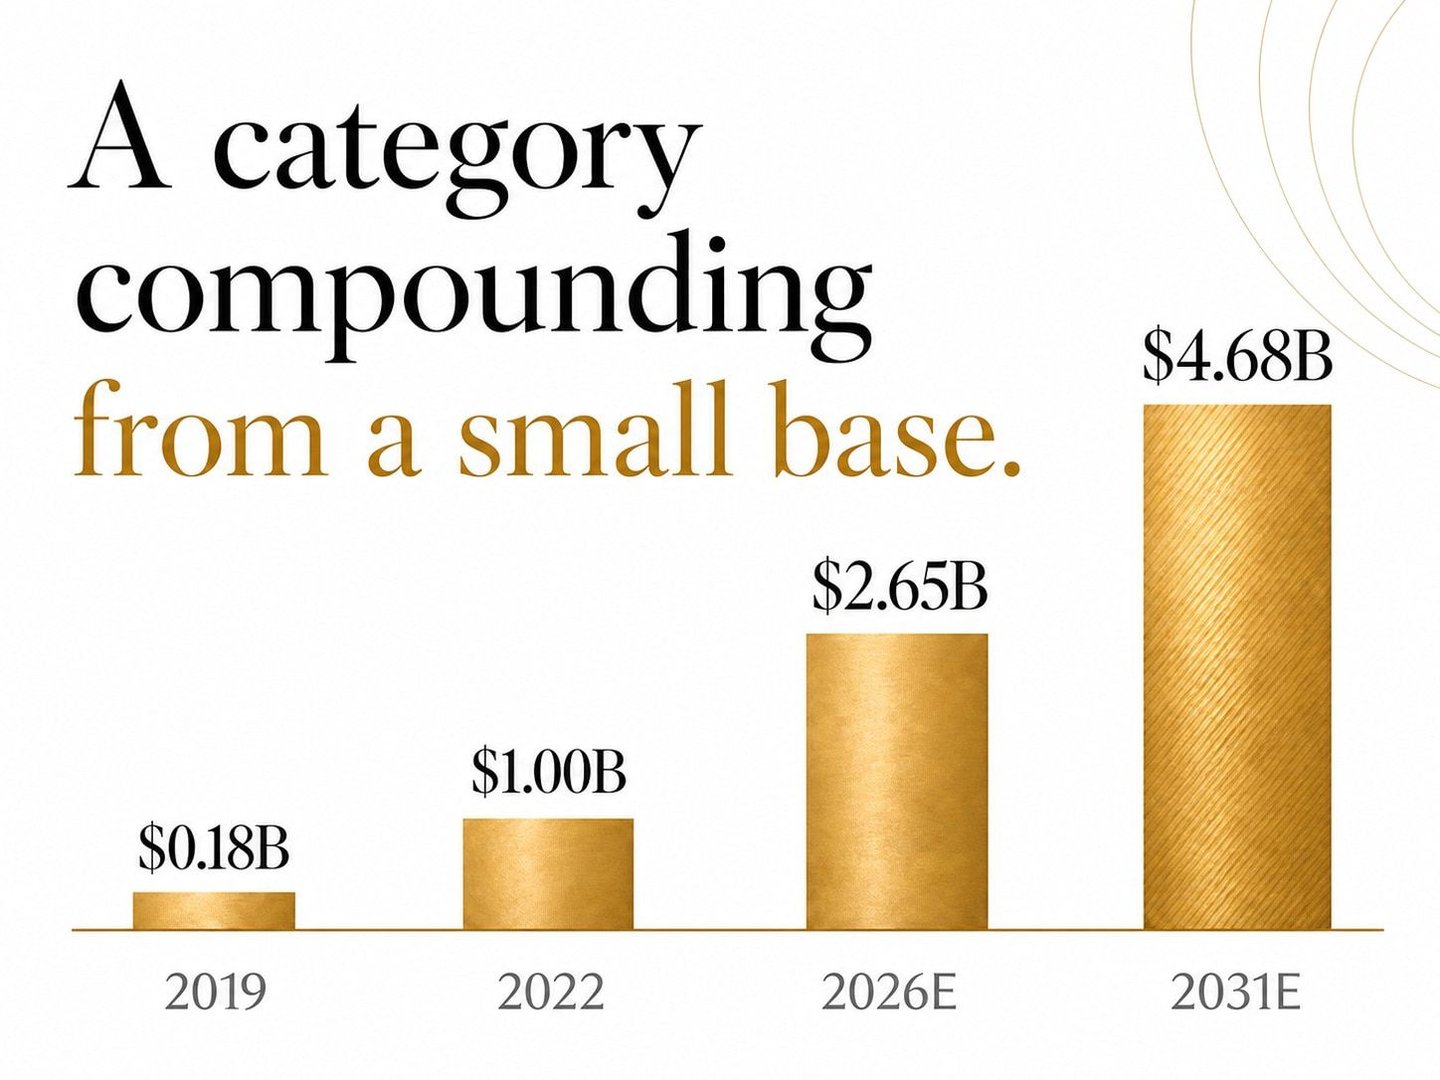

Modeled operator revenue for futures and FX-pair evaluation firms, CFD-only economics excluded. Independent published estimates put all retail prop direct revenue at $4.0–4.5B for 2026. Base case assumes a 12% CAGR to 2031; bear 5.1%, bull 18.9%. These are modeled figures, not audited industry statistics. Independent industry analysis also describes a broader ecosystem value of roughly $20 billion once partner brokerage economics and nominally allocated capital are included. The chart models direct operator revenue only, the smaller and harder number.

The category is large enough to matter and still early enough for a new operator to take a real position. 

It is also consolidating: the firms pulling ahead are the ones that own their platform and have a genuine route to live markets, not the ones with the cheapest challenge.

Business Model
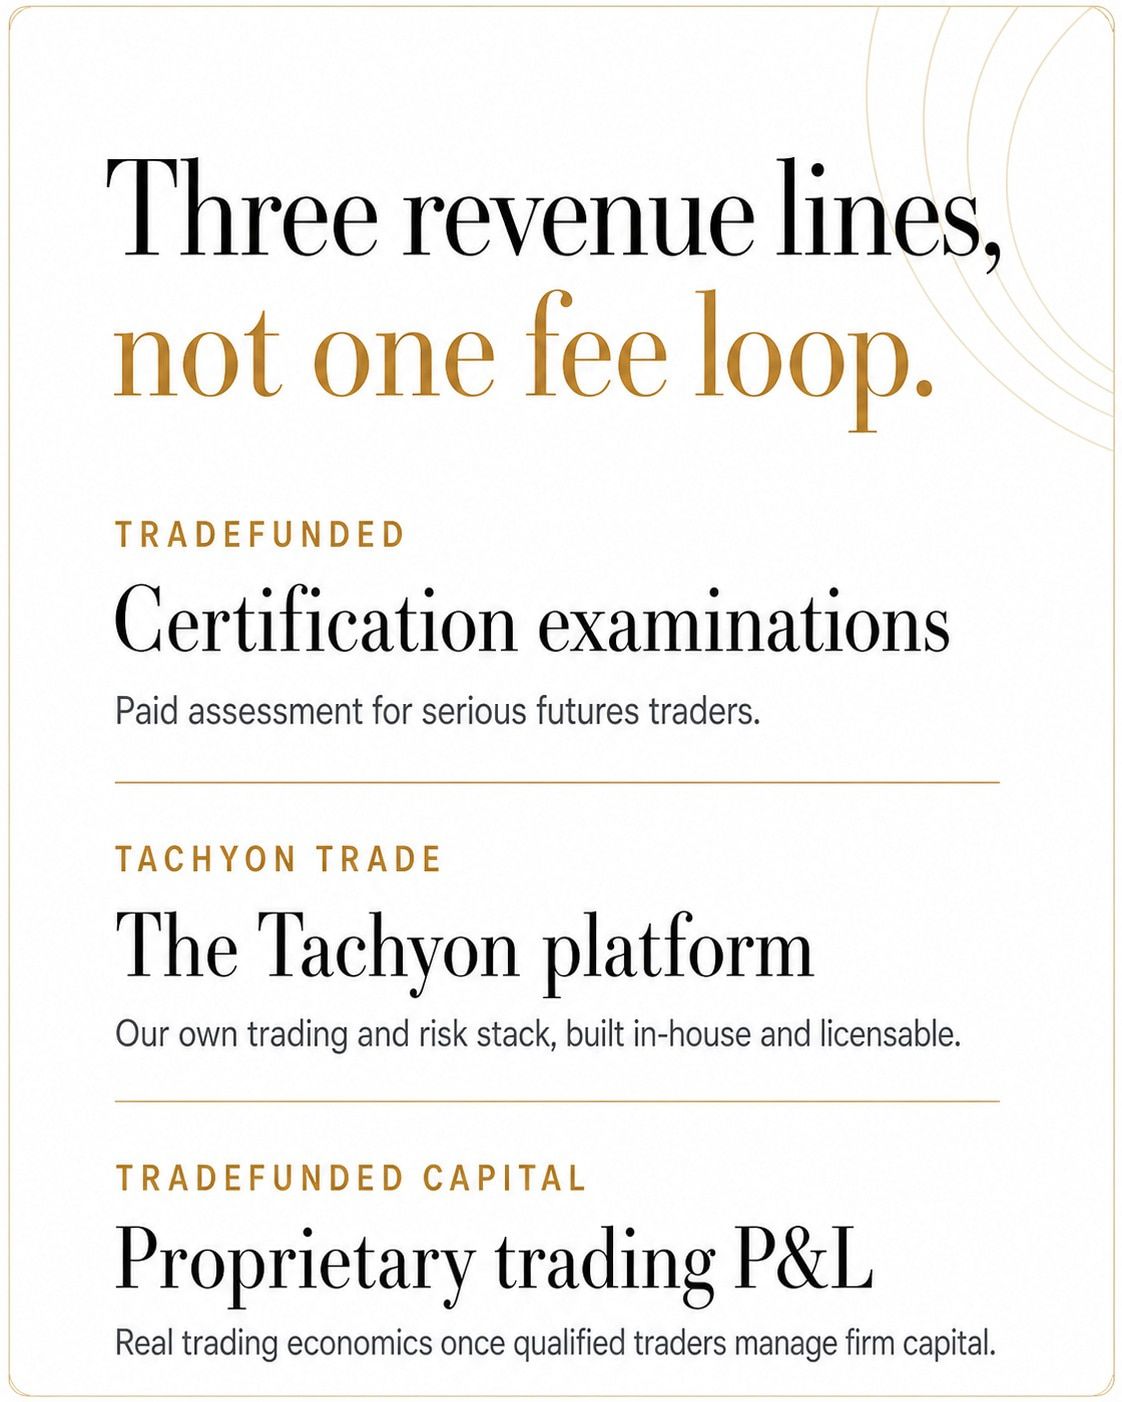


Examinations fund the funnel. Tachyon improves who we select. Qualified traders create the long-term upside. Each line supports a different stage, and none of them requires candidates to keep failing.

What that model can produce, at scale, looks like this.
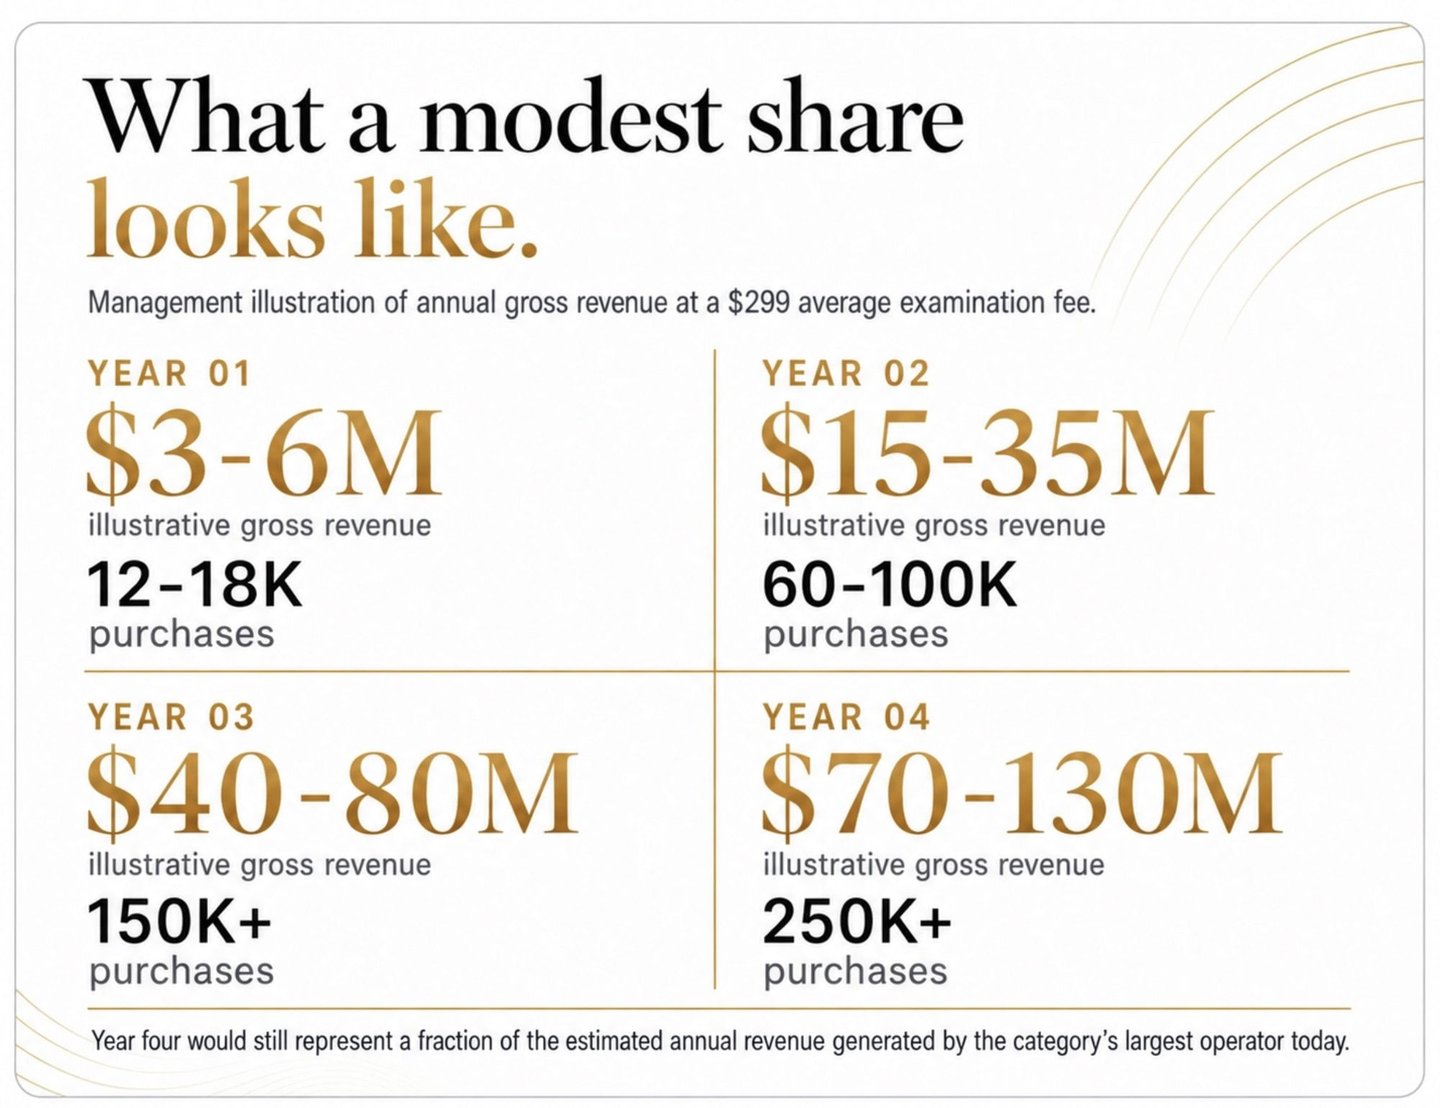
Management illustration at a $299 average examination fee. Above projection is based on roughly 2,200 monthly examination purchases, only about 0.1–0.2% of the modeled futures and FX category. Dollar figures represent illustrative gross revenue, not profit, EBITDA or net income. Projections are illustrative, not guarantees, and actual results will depend on launch timing, capacity, demand, operating costs and execution.

Forward-looking statement: These projections are illustrative estimates based on management’s current assumptions and are not guarantees of future performance. Actual results may differ materially due to risks, uncertainties, and factors beyond the company’s control. Investors should not place undue reliance on these projections. Please review Republic’s Forward-Looking Financial Projections Disclaimer.

What Comes Next


The model is new, and it is not carrying the structural problems the first generation was built on. 

There is more in development than the examination and the platform. We will show it when it ships.


Benefits
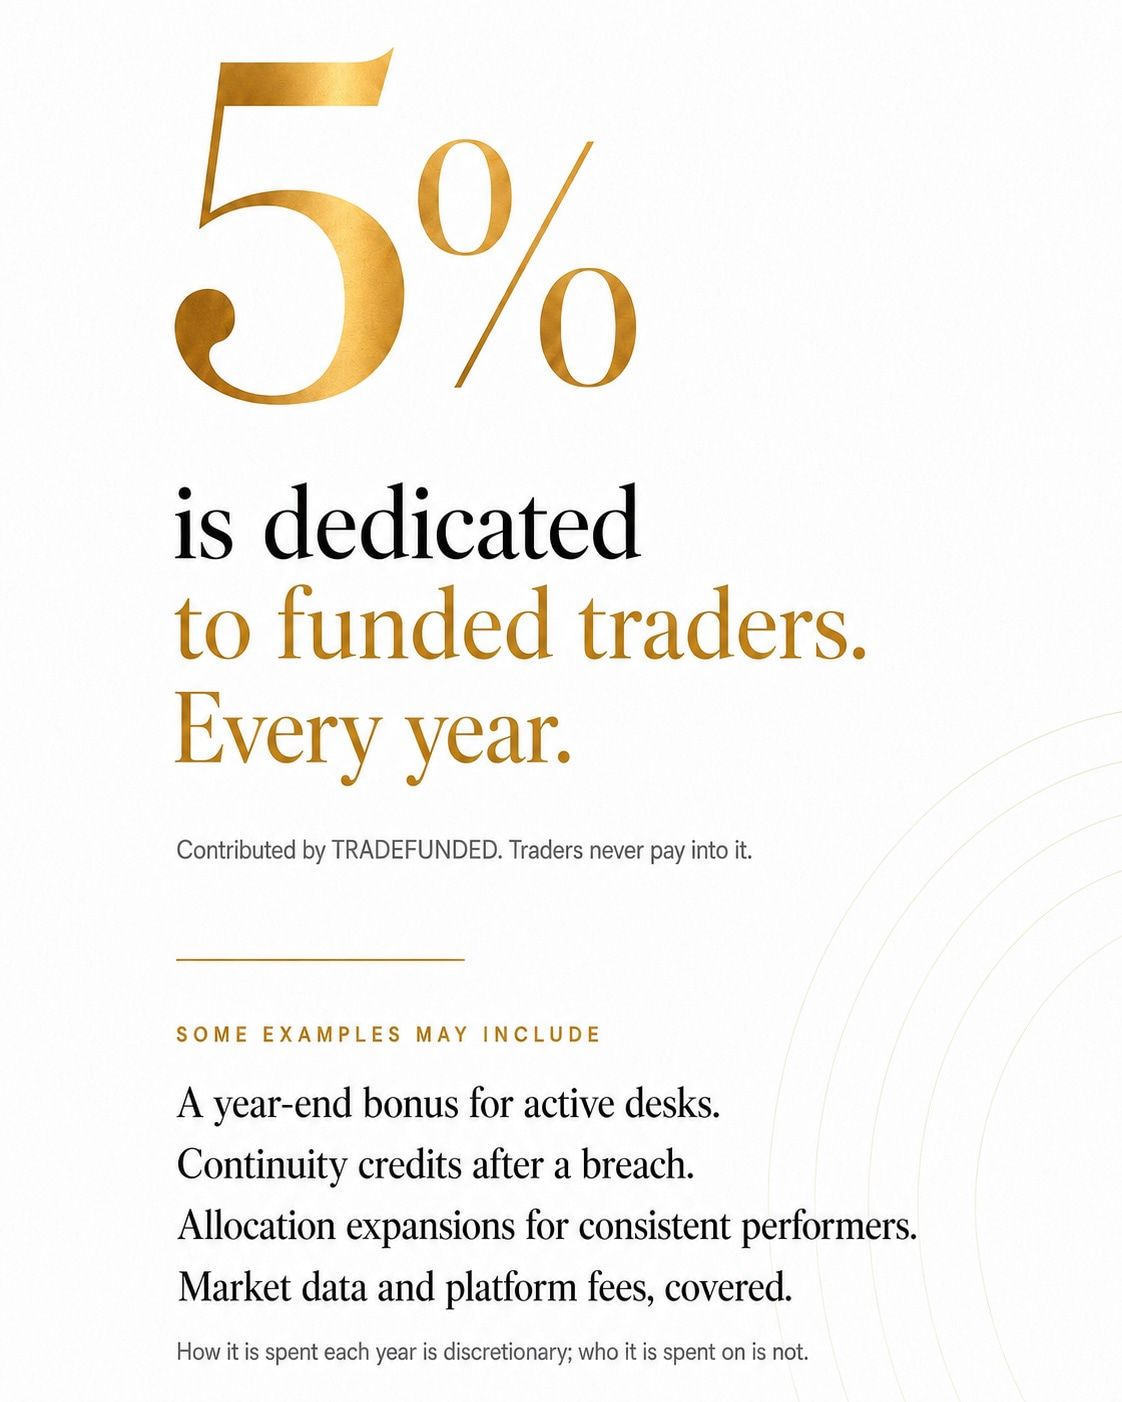


5% of Pre-Distribution Cash is allocated to TRADEFUNDED CAPITAL. Pre-Distribution Cash means cash available for distribution after company obligations and reasonable reserves are accounted for.

The Five Percent exists because of what this industry does to its best people.


That is the trader this firm is built for, and there are a lot of them.


We are not building another temporary stop in a trader's journey. 

We are building the place the journey can continue, and the Five Percent is the part of that written down where it cannot quietly disappear. 

What it funds each year is discretionary. Who it is spent on is not.

Leadership
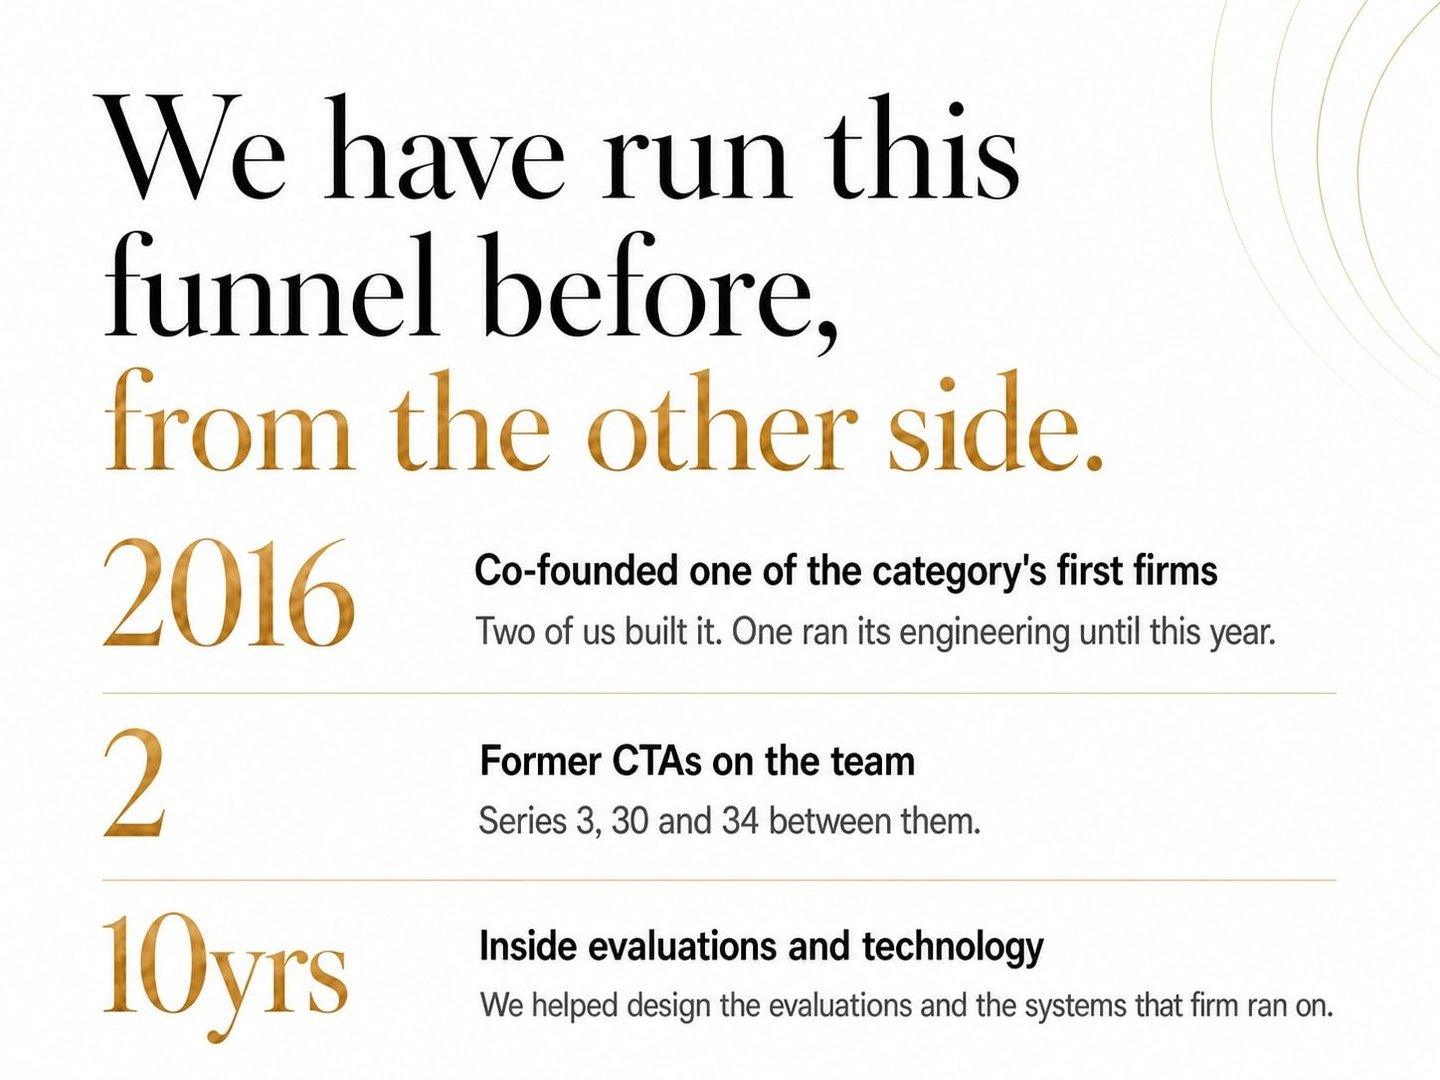


The same team, by role.
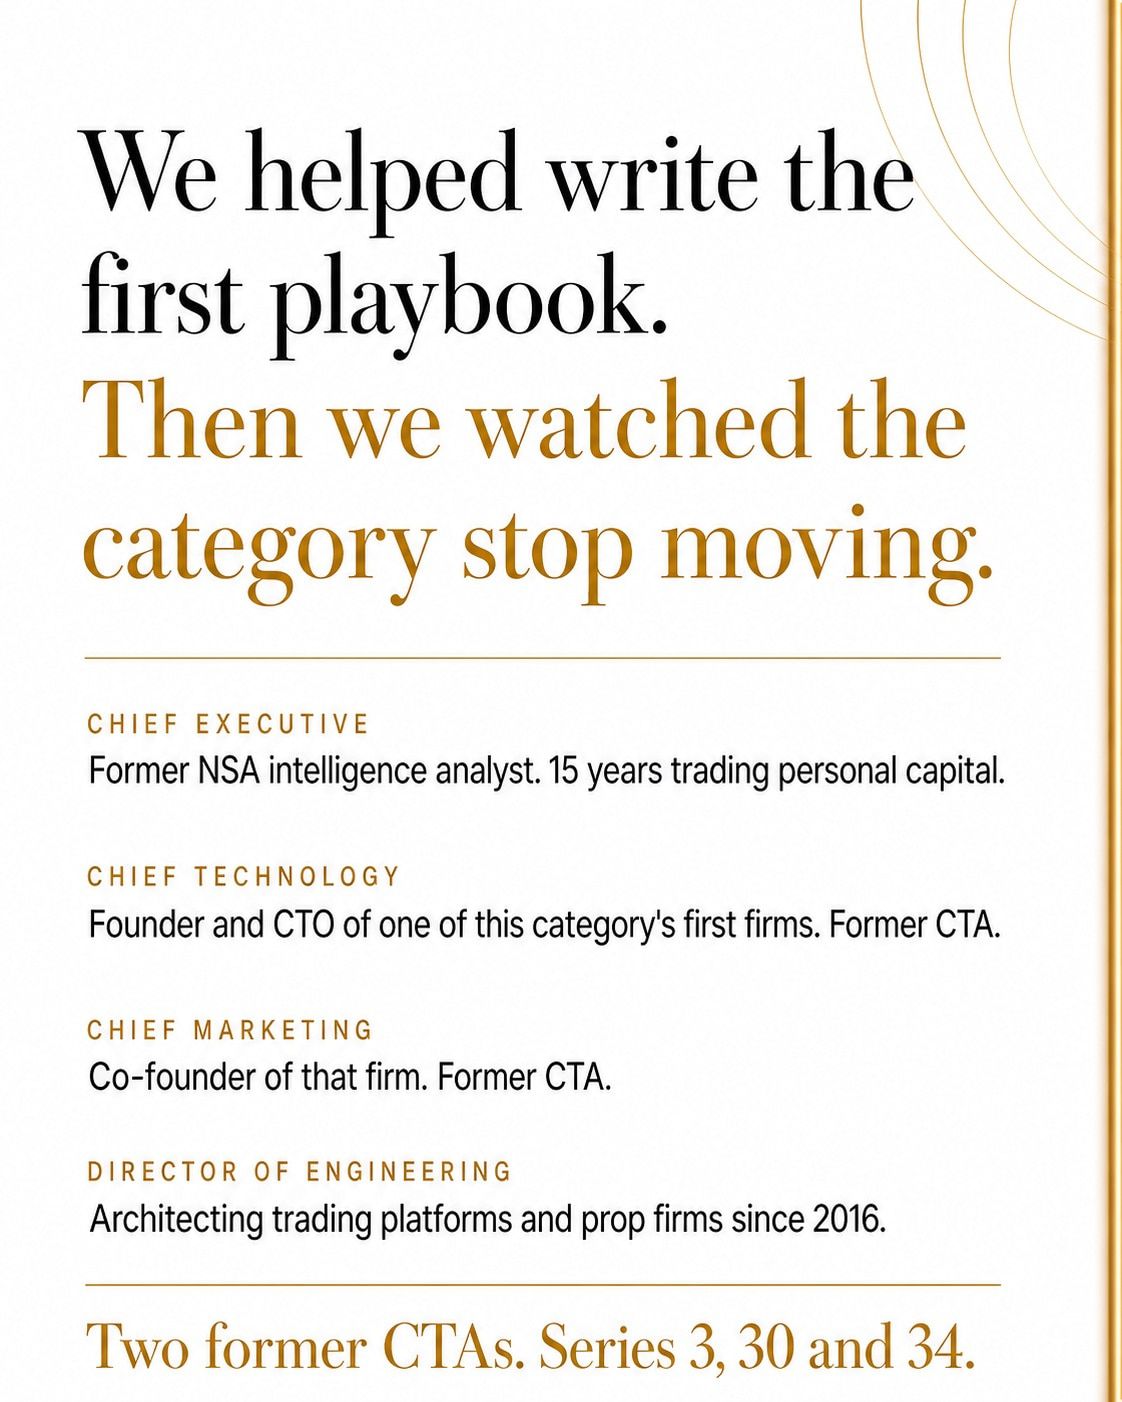


Officers, ownership and risk factors are set out in the Form C.

Community Ownership


This category has spent its whole existence working for one side. 

The firm sells the exam, the firm writes the rules, the firm keeps what is left. The trader is the other side of that trade.

We would rather not run it that way, so we are letting the people who use the firm own part of it. 

Trader on one side, owner on the other. The same person, on both sides of the table.
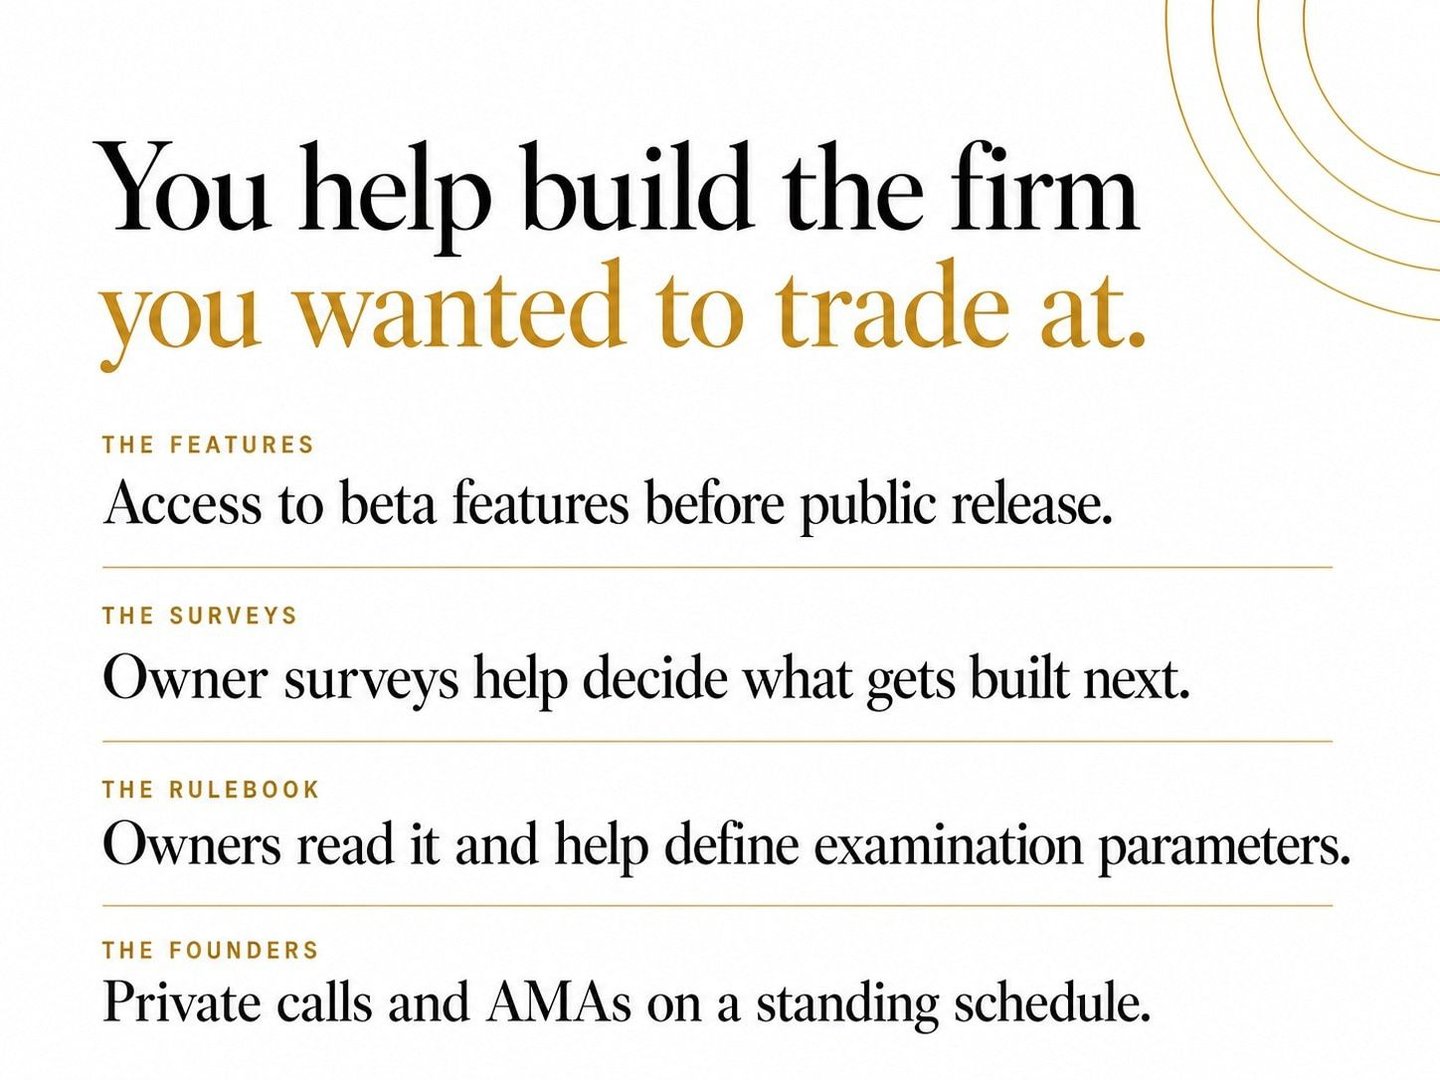


That is not a badge, and the stake is not symbolic.


Backing the raise comes with its own ladder.
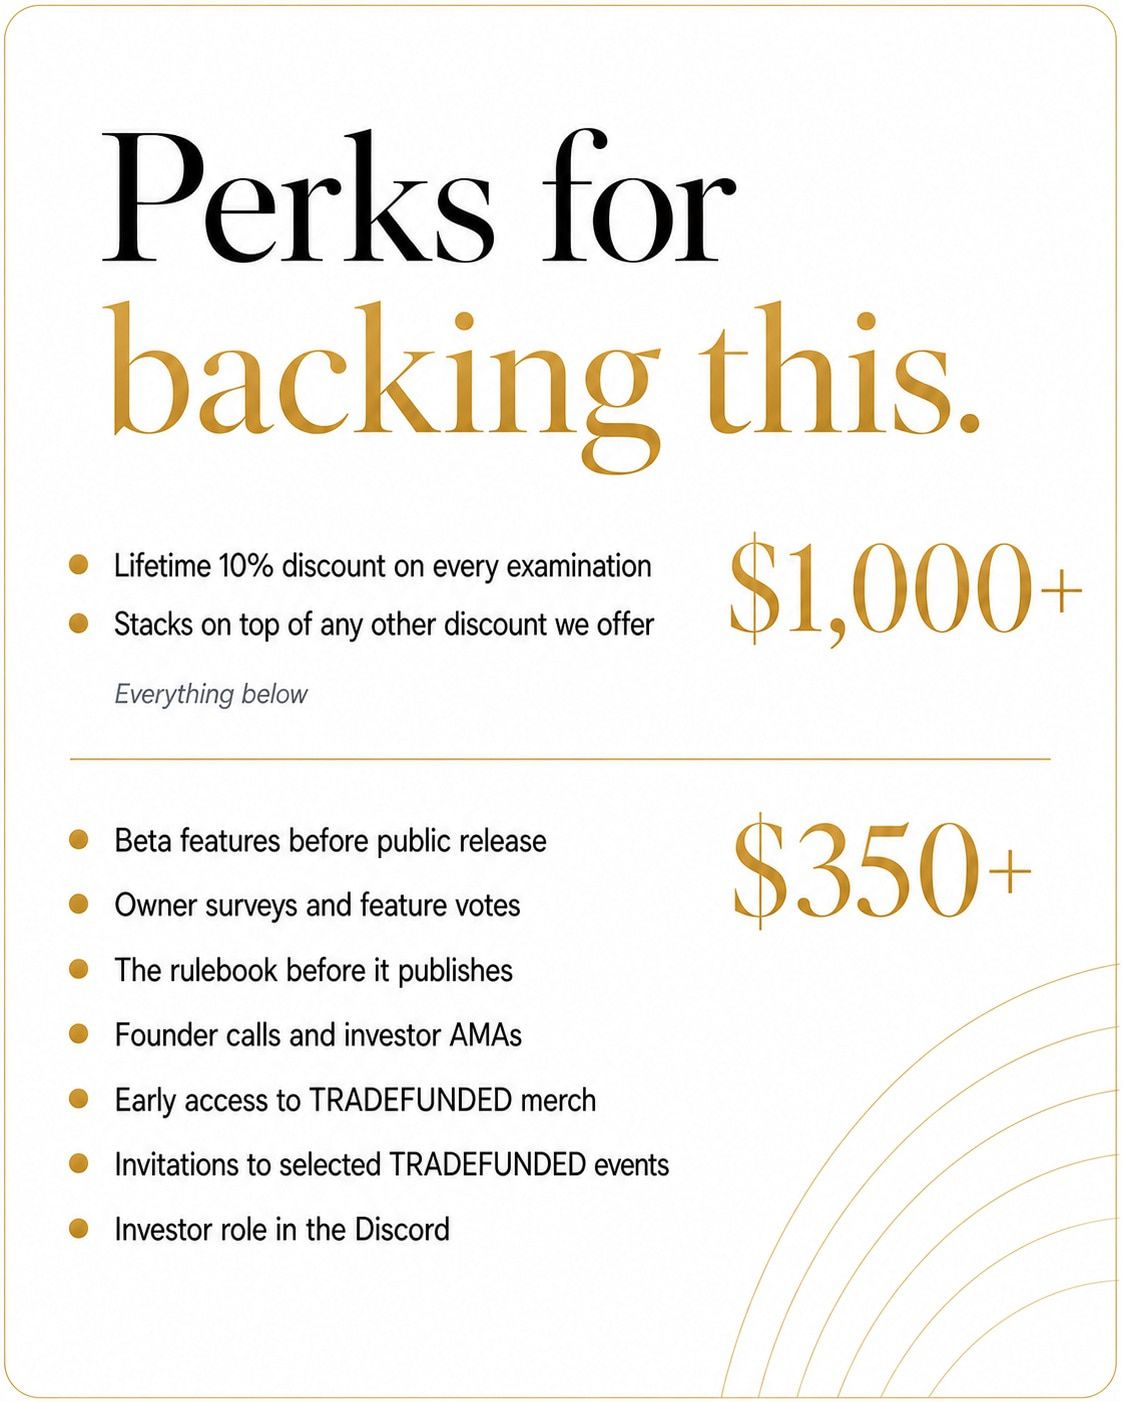


All allocations come from revenue, not from the raise. Offering proceeds never become trading capital.


Summary


The category's first act proved people will pay to be evaluated. The second act belongs to whoever builds the firm they stay at afterward. 

That is what we are building, and the full model publishes on launch day, in the rulebook every trader reads before they buy.
$

Deal terms


Funding range
$75K / $680K
5% of $75K minimum offering amount has been reached.

TRADEFUNDED LLC must achieve its minimum goal of $75K before the deadline.
The maximum amount the offering can raise is $680K.
Learn more
Minimum investment
$350
The smallest investment amount the issuer is accepting in this offering.
Maximum investment
$150K
The largest investment amount the issuer is accepting in this offering.
Security type
Units shares
Common stock issued by TradeFunded LLC
Learn more
Deadline
December 15, 2026
TRADEFUNDED LLC campaign will end on .
Learn more
How it works

Documents

Republic (OpenDeal Portal LLC, CRD #283874) is hosting this Reg CF securities offering by TradeFunded LLC. View the official SEC filing and all updates:
Official SEC Logo Form C SEC.gov
Company documents
Subscription Agreement TradeFunded LLC - Form C.pdf

Bonus perks

In addition to your Units shares, you'll receive perks for investing in TRADEFUNDED LLC.
Invest
$350
Receive
  • Beta features before public release
  • Owner surveys and feature votes
  • The rulebook before it publishes
  • Founder calls and investor AMAs
  • Early access to TRADEFUNDED merch
  • Invitations to selected TRADEFUNDED events
  • Investor role in the Discord
Invest $350
Invest
$1,000
Receive
  • Lifetime 10% discount on examinations, stacked on top of any other discounts
  • All perks for lower levels
Invest $1,000

About TRADEFUNDED LLC

Legal Name
TradeFunded LLC
Founded
Feb 2026
Form
Delaware LLC
Employees
6
Website
tradefunded.com
Social Media
Headquarters
Google Map location of of TRADEFUNDED LLC
8 The Green , Dover, DE
Headquarters
8 The Green, Dover, DE, United States 19901

TRADEFUNDED LLC Team
Everyone helping build TRADEFUNDED LLC, not limited to employees

Profile picture of Christopher Price
Christopher Price
Co-Founder & CEO
Profile picture of David Lojko
David Lojko
Co-Founder & CMO
Profile picture of Ryan Masten
Ryan Masten
Co-Founder & CTO
Profile picture of Jared White
Jared White
Director of Engineering
4 more team members
Christopher Price
Co-Founder & CEO
David Lojko
Co-Founder & CMO
Ryan Masten
Co-Founder & CTO
Jared White
Director of Engineering

FAQ

Which countries or states are not permitted to open a Custody Account with BitGo?

Which countries or states are not permitted to open a Custody Account with BitGo?

  • Anguilla

  • Belarus

  • Belgium

  • Bermuda

  • Bonaire, Sint Eustatius and Saba

  • Cuba

  • El Salvador

  • France

  • Grenada

  • Guadeloupe

  • Haiti

  • India

  • Indonesia

  • Iran

  • Israel

  • Jamaica

  • Japan

  • Montserrat

  • North Korea

  • Qatar

  • Russia

  • Saint Kitts and Nevis

  • Syria

  • Turks and Caicos Islands

  • Venezuela

  • Vermont, USA

What is a custodian and what is a custodial account?

What is a custodian and what is a custodial account?

A custodian is a qualified third-party entity that acts as a legal holder of securities. An investor will open a custodial account with the qualified custodian, which is used to hold investments, namely the securities in a company. A custodial account allows you to name a beneficiary and accept payments such as dividends distributions or cash payouts. Custodial accounts are not managed or held by Republic; instead, they are managed by the custodian who works with the issuer raising on the platform. The custodian of this offering is BitGo Trust Company.
Why use a custodial account?

Why use a custodial account?

Companies will utilize a custodian to ensure that all securities they offer in their campaign are in one place. This means if a liquidity event or any other material event in respect to the securities occurs, the company can look to the custodian to service the securities, rather than each individual investor. 

For investors, utilizing a custodian safeguards their investment, or security interest, with a qualified financial institution. Having a custodial account allows for easier transfers and creates additional layers of protection for your securities. For companies, it can increase efficiency by reducing their cap table management costs and creating a single-line item, making future funding rounds easier.

Will I have to set up a custodial account? What is the process?

Will I have to set up a custodial account? What is the process?

Yes, since the company is utilizing a custodian, all investors in the offering will be required to create a custodial account with BitGo Trust Company and enter into an omnibus nominee agreement.

The custodial account creation process is hosted in our investment checkout system, meaning you will commit your investment and establish your account with BitGo all at once. During investment checkout, you will be automatically prompted to review and sign certain custodial documents with BitGo. In addition, you may be asked to provide certain information to verify your identity. Once completed, you will receive an email confirming your investment commitment.

I’m being told my custody account is in manual review, what should I do?

I’m being told my custody account is in manual review, what should I do?

BitGo reviews accounts that require manual review on a daily basis. Please expect to receive confirmation of your account being opened or to hear further guidance from our team within 24-48 hours.
Does it cost me anything to open a custodial account with BitGo Trust Company?

Does it cost me anything to open a custodial account with BitGo Trust Company?

Right now, there are no costs for investors to open a custodial account. Custodial accounts do sometimes have a low annual cost to maintain; however, such costs are covered for the investor in this offering at this time.
Why would a company use a custodian like BitGo?

Why would a company use a custodian like BitGo?

Companies will utilize a custodian to ensure that all securities they offer in their campaign are in one place. This means if a liquidity event or any other material event in respect to the securities occurs, the company can look to the custodian to service the securities, rather than each individual investor. 

For investors, utilizing a custodian safeguards their investment, or security interest, with a qualified financial institution. Having a custodial account allows for easier transfers and creates additional layers of protection for your securities. For companies, it can increase efficiency by reducing their cap table management costs and creating a single-line item, making future funding rounds easier.

What are the risks associated with investing in equity securities?

What are the risks associated with investing in equity securities?

Equity security investments are subject to market fluctuations, company-specific risks, and general economic conditions. Prices can be volatile, and there is risk of losing the invested capital. Remember, investing always carries risks, and it's essential to conduct thorough research or consult with a financial advisor before making investment decisions.
How do I earn a return?

How do I earn a return?

We are issuing equity in our company. You may realize returns if the company “exits,” meaning it is acquired or goes public at a higher price than you paid for it, or if you sell the securities at a higher price than you purchased them for. There is also a risk that you could lose your entire investment if the company fails. Startup investing is risky, so there’s no guarantee of a return on this kind of investment. It’s always best to refer to the individual offering documents provided by the company to understand your investment risks.

Still have questions? Check the discussion section.
Show all FAQ

Risks

We have a limited operating history upon which you can evaluate our performance, and accordingly, our prospects must be considered in light of the risks that any new company encounters.

The Issuer is still in an early phase and we are just beginning to implement our business plan. There can be no assurance that we will ever operate profitably. The likelihood of our success should be considered in light of the problems, expenses, difficulties, complications and delays usually encountered by early stage companies. The Issuer may not be successful in attaining the objectives necessary for it to overcome these risks and uncertainties.

The Custodian shall serve as the legal title holder of the Securities. Investors will only obtain a beneficial ownership in the Securities.

The Issuer and the Investor shall appoint and authorize the qualified third-party Custodian for the benefit of the Investor, to hold the Securities in registered form in the Custodian’s name or the name of the Custodian’s nominees for the benefit of the Investor and Investor’s permitted assigns. The Custodian may take direction from the Manager Committee, who will act on behalf of the Investors, and the Custodian may be permitted to rely on the Manager Committee’s instructions related to the Securities. Investors may never become an equity holder, merely a beneficial owner of an equity interest.

Investors will grant a proxy authority to act on their behalf.

In connection with investing in this Offering to purchase the Securities, Investors will designate the Proxy (as defined above) to act as proxy on behalf of Investors in respect to instructions related to the Securities. The Proxy will be entitled, among other things, to exercise any voting rights (if any) conferred upon the holder of the Securities and to execute on behalf of an investor any consents, approvals and waivers. Thus, by participating in the Offering, Investors will grant broad discretion to the Proxy to take various actions on their behalf, and Investors will essentially not be able to vote upon matters related to the governance and affairs of the Issuer nor take or effect actions that might otherwise be available to holders of the Securities. Investors should not participate in the Offering unless he, she or it is willing to waive or assign certain rights that might otherwise be afforded to a holder of the Securities to the Proxy and grant broad authority to the Proxy to take certain actions on behalf of the Investor.

Damage to our reputation could negatively impact our business, financial condition and results of operations.

Our reputation and the quality of our brand are critical to our business and success in existing markets, and will be critical to our success as we enter new markets. Any incident that erodes consumer loyalty for our brand could significantly reduce its value and damage our business. We may be adversely affected by any negative publicity, regardless of its accuracy. Also, there has been a marked increase in the use of social media platforms and similar

devices, including blogs, social media websites and other forms of internet-based communications that provide individuals with access to a broad audience of consumers and other interested persons. The availability of information on social media platforms is virtually immediate as is its impact. Information posted may be adverse to our interests or may be inaccurate, each of which may harm our performance, prospects or business. The harm may be immediate and may disseminate rapidly and broadly, without affording us an opportunity for redress or correction.

Global crises and geopolitical events, including without limitation, COVID-19 can have a significant effect on our business operations and revenue projections.

A significant outbreak of contagious diseases, such as COVID-19, in the human population could result in a widespread health crisis. Additionally, geopolitical events, such as wars or conflicts, could result in global disruptions to supplies, political uncertainty and displacement. Each of these crises could adversely affect the economies and financial markets of many countries, including the United States where we principally operate, resulting in an economic downturn that could reduce the demand for our products and services and impair our business prospects, including as a result of being unable to raise additional capital on acceptable terms, if at all.

The amount of capital the Issuer is attempting to raise in this Offering may not be enough to sustain the Issuer’s current business plan.

In order to achieve the Issuer’s near and long-term goals, the Issuer may need to procure funds in addition to the amount raised in the Offering. There is no guarantee the Issuer will be able to raise such funds on acceptable terms or at all. If we are not able to raise sufficient capital in the future, we may not be able to execute our business plan, our continued operations will be in jeopardy and we may be forced to cease operations and sell or otherwise transfer all or substantially all of our remaining assets, which could cause an Investor to lose all or a portion of their investment.

We may face potential difficulties in obtaining capital.

We may have difficulty raising needed capital in the future as a result of, among other factors, our lack of revenues from sales, as well as the inherent business risks associated with our Issuer and present and future market conditions. We will require additional funds to execute our business strategy and conduct our operations. If adequate funds are unavailable, we may be required to delay, reduce the scope of or eliminate one or more of our research, development or commercialization programs, product launches or marketing efforts, any of which may materially harm our business, financial condition and results of operations.

We may implement new lines of business or offer new products and services within existing lines of business.

1 The Issuer owns ninety-eight percent (98%) of TRADEFUNDED Capital LLC’s outstanding equity interests.

As an early-stage company, we may implement new lines of business at any time. There are substantial risks and uncertainties associated with these efforts, particularly in instances where the markets are not fully developed. In developing and marketing new lines of business and/or new products and services, we may invest significant time and resources. Initial timetables for the introduction and development of new lines of business and/or new products or services may not be achieved, and price and profitability targets may not prove feasible. We may not be successful in introducing new products and services in response to industry trends or developments in technology, or those new products may not achieve market acceptance. As a result, we could lose business, be forced to price products and services on less advantageous terms to retain or attract clients or be subject to cost increases. As a result, our business, financial condition or results of operations may be adversely affected.

We rely on other companies to provide components and services for our products.

We depend on suppliers and contractors to meet our contractual obligations to our customers and conduct our operations. Our ability to meet our obligations to our customers may be adversely affected if suppliers or contractors do not provide the agreed-upon supplies or perform the agreed-upon services in compliance with customer requirements and in a timely and cost-effective manner. Our suppliers may be unable to quickly recover from natural disasters and other events beyond their control and may be subject to additional risks such as financial problems that limit their ability to conduct their operations. The risk of these adverse effects may be greater in circumstances where we rely on only one or two contractors or suppliers for a particular component. Our products may utilize custom components available from only one source. Continued availability of those components at acceptable prices, or at all, may be affected for any number of reasons, including if those suppliers decide to concentrate on the production of common components instead of components customized to meet our requirements. The supply of components for a new or existing product could be delayed or constrained, adversely affecting our business and results of operations.

We rely on various intellectual property rights, including trademarks, in order to operate our business.

The Issuer relies on certain intellectual property rights to operate its business. The Issuer’s intellectual property rights may not be sufficiently broad or otherwise may not provide us a significant competitive advantage. In addition, the steps that we have taken to maintain and protect our intellectual property may not prevent it from being challenged, invalidated, circumvented or designed-around, particularly in countries where intellectual property rights are not highly developed or protected. In some circumstances, enforcement may not be available to us because an infringer has a dominant intellectual property position or for other business reasons, or countries may require compulsory licensing of our intellectual property. Our failure to obtain or maintain intellectual property rights that convey competitive advantage, adequately protect our intellectual property or detect or prevent circumvention or unauthorized use of such property, could adversely impact our competitive position and results of operations. We also rely on nondisclosure and noncompetition agreements with employees, consultants and other parties to protect, in part, trade secrets and other proprietary rights. There can be no assurance that these agreements will adequately protect our trade secrets and other proprietary rights and will not be breached, that we will have adequate remedies for any breach, that others will not independently develop substantially equivalent proprietary information or that third parties will not otherwise gain access to our trade secrets or other proprietary rights. As we expand our business, protecting our intellectual property will become increasingly important. The protective steps we have taken may be inadequate to deter our competitors from using our proprietary information. In order to protect or enforce our patent rights, we may be required to initiate litigation against third parties, such as infringement lawsuits. Also, these third parties may assert claims against us with or without provocation. These lawsuits could be expensive, take significant time and could divert management’s attention from other business concerns. The law relating to the scope and validity of claims in the technology field in which we operate is still evolving and, consequently, intellectual property positions in our industry are generally uncertain. We cannot assure you that we will prevail in any of these potential suits or that the damages or other remedies awarded, if any, would be commercially valuable.

We rely on third-party service providers, including clearing, market-data, payment-processing, banking and technology providers, to operate our business.

Our operations depend on services provided by third parties, including futures commission merchant and clearing relationships, exchange connectivity and market-data feeds, payment processors that collect examination fees, banking partners and the cloud-hosting and software vendors that support the Tachyon platform. These providers may fail to perform, may suffer outages, insolvency or security incidents, may change their pricing or terms or may terminate their relationships with us on short notice. Certain of these services are obtained from a single provider or a limited number of providers, and replacement providers may not be available on acceptable terms or at all. Any interruption

in these services could disrupt our examinations, our proprietary trading and our platform licensing and could materially harm our business, financial condition and results of operations.

Our intellectual property rights are limited; our trademark application is pending and may not be granted, and we may be unable to protect our proprietary technology.

The Issuer’s intellectual property consists principally of the Tachyon trading and risk-management platform, related trade secrets, know-how and proprietary processes, and a pending U.S. service mark application for the TRADEFUNDED mark (Serial No. 99893727, filed June 18, 2026). The application has not been granted and may be refused, opposed or abandoned, and the Issuer may be unable to obtain or maintain a registration or to prevent others from using confusingly similar marks. The Issuer does not own any issued patents or registered copyrights, and its unregistered rights may not provide a significant competitive advantage or prevent competitors from independently developing similar platforms, examinations or business methods. Licensing the Tachyon platform to third parties increases the risk of unauthorized use, reverse engineering or misappropriation. Enforcing intellectual property rights, or defending against claims that the Issuer infringes the rights of others, could be expensive and protracted, could divert management’s attention and may not be successful.

The Issuer’s success depends on the experience and skill of the Manager Committee, its executive officers and key employees.

We are dependent on our Manager Committee, executive officers and key employees. These persons may not devote their full time and attention to the matters of the Issuer. The loss of our Manager Committee, executive officers and key employees could harm the Issuer’s business, financial condition, cash flow and results of operations.

Our executive officers and key persons hold positions at other entities and will not devote their full time to the Issuer.

Certain of the Issuer’s executive officers and key persons hold concurrent positions at, or previously held senior positions at, other entities, including entities operating in the category in which the Issuer competes. Certain executive officers also serve as the designated representative of an entity that holds Units and participates in the management of the Issuer. As a result, the attention of key persons is divided, business opportunities, personnel or technology may be allocated to another enterprise rather than to the Issuer, and the individuals directing the Issuer’s operations may hold interests that diverge from those of Investors purchasing Securities in this Offering. A current or former employer of a key person may also assert restrictive covenants, trade-secret or intellectual property claims against that person or against the Issuer, any of which could be costly to defend, could divert management attention and could limit the Issuer’s use of its technology, content or personnel.

The Issuer seeks to mitigate these risks through, as applicable, governance approval requirements for affiliate transactions, disclosure and recusal obligations for conflicted persons, and written confidentiality and invention-assignment agreements with executive officers and key persons. These measures do not eliminate the underlying conflicts, and no assurance can be given that any conflict will be resolved in a manner favorable to the Issuer or to Investors.

Although dependent on certain key personnel, the Issuer does not have any key person life insurance policies on any such people.

We are dependent on certain key personnel in order to conduct our operations and execute our business plan, however, the Issuer has not purchased any insurance policies with respect to those individuals in the event of their death or disability. Therefore, if any of these personnel die or become disabled, the Issuer will not receive any compensation to assist with such person’s absence. The loss of such person could negatively affect the Issuer and our operations. We have no way to guarantee key personnel will stay with the Issuer, as many states do not enforce non-competition agreements, and therefore acquiring key man insurance will not ameliorate all of the risk of relying on key personnel.

Our business could be negatively impacted by cyber security threats, attacks and other disruptions.

We continue to face advanced and persistent attacks on our information infrastructure where we manage and store various proprietary information and sensitive/confidential data relating to our operations. These attacks may include sophisticated malware (viruses, worms, and other malicious software programs) and phishing emails that attack our products or otherwise exploit any security vulnerabilities. These intrusions sometimes may be zero-day malware that are difficult to identify because they are not included in the signature set of commercially available antivirus scanning programs. Experienced computer programmers and hackers may be able to penetrate our network security and misappropriate or compromise our confidential information or that of our customers or other third-parties, create system disruptions, or cause shutdowns. Additionally, sophisticated software and applications that we produce or procure from third-parties may contain defects in design or manufacture, including “bugs” and other problems that could unexpectedly interfere with the operation of the information infrastructure. A disruption, infiltration or failure of our information infrastructure systems or any of our data centers as a result of software or hardware malfunctions, computer viruses, cyber-attacks, employee theft or misuse, power disruptions, natural disasters or accidents could cause breaches of data security, loss of critical data and performance delays, which in turn could adversely affect our business.

Security breaches of confidential customer information, in connection with our electronic processing of credit and debit card transactions, or confidential employee information may adversely affect our business.

Our business requires the collection, transmission and retention of personally identifiable information, in various information technology systems that we maintain and in those maintained by third parties with whom we contract to provide services. The integrity and protection of that data is critical to us. The information, security and privacy requirements imposed by governmental regulation are increasingly demanding. Our systems may not be able to satisfy these changing requirements and customer and employee expectations, or may require significant additional investments or time in order to do so. A breach in the security of our information technology systems or those of our service providers could lead to an interruption in the operation of our systems, resulting in operational inefficiencies and a loss of profits. Additionally, a significant theft, loss or misappropriation of, or access to, customers’ or other proprietary data or other breach of our information technology systems could result in fines, legal claims or proceedings.

The use of Individually identifiable data by our business, our business associates and third parties is regulated at the state, federal and international levels.

The regulation of individual data is changing rapidly, and in unpredictable ways. A change in regulation could adversely affect our business, including causing our business model to no longer be viable. Costs associated with information security – such as investment in technology, the costs of compliance with consumer protection laws and costs resulting from consumer fraud – could cause our business and results of operations to suffer materially. Additionally, the success of our online operations depends upon the secure transmission of confidential information over public networks, including the use of cashless payments. The intentional or negligent actions of employees, business associates or third parties may undermine our security measures. As a result, unauthorized parties may obtain access to our data systems and misappropriate confidential data. There can be no assurance that advances in computer capabilities, new discoveries in the field of cryptography or other developments will prevent the compromise of our customer transaction processing capabilities and personal data. If any such compromise of our security or the security of information residing with our business associates or third parties were to occur, it could have a material adverse effect on our reputation, operating results and financial condition. Any compromise of our data security may materially increase the costs we incur to protect against such breaches and could subject us to additional legal risk.

The Issuer is not subject to Sarbanes-Oxley regulations and may lack the financial controls and procedures of public companies.

The Issuer may not have the internal control infrastructure that would meet the standards of a public company, including the requirements of the Sarbanes-Oxley Act of 2002. As a privately-held (non-public) issuer, the Issuer is

currently not subject to the Sarbanes-Oxley Act of 2002, and its financial and disclosure controls and procedures reflect its status as a development stage, non-public company. There can be no guarantee that there are no significant deficiencies or material weaknesses in the quality of the Issuer’s financial and disclosure controls and procedures. If it were necessary to implement such financial and disclosure controls and procedures, the cost to the Issuer of such compliance could be substantial and could have a material adverse effect on the Issuer’s results of operations.

We operate in a highly regulated environment, and if we are found to be in violation of any of the federal, state, or local laws or regulations applicable to us, our business could suffer.

We operate in the financial services sector and are subject to a wide range of federal, state and local laws and regulations, including laws and rules administered by the U.S. Commodity Futures Trading Commission, the National Futures Association, the U.S. Securities and Exchange Commission and state financial regulators, as well as consumer-protection, advertising, data-privacy, anti-money-laundering, tax, wage-hour, anti-discrimination, whistleblower and other employment practices laws and regulations, and we expect our compliance costs to increase going forward. The violation of these or future requirements or laws and regulations could result in administrative, civil, or criminal sanctions against us, which may include fines, a cease and desist order against the subject operations or even revocation or suspension of our license to operate the subject business. As a result, we have incurred and will continue to incur capital and operating expenditures and other costs to comply with these requirements and laws and regulations.

Our revenue is concentrated in, and dependent on the interdependence of, three lines of business.

A disruption to any one of our revenue lines may impair the others. Our revenue lines include the following: (1) certification examination fees, (2) licensing of the Tachyon platform, and (3) net proprietary trading profit and loss generated by TRADEFUNDED Capital and retained after trader compensation, which the Issuer may receive only in the form of distributions from TRADEFUNDED Capital. A decline in examination volume reduces the pipeline of qualified traders and, in turn, our trading results; weak trading results or reputational harm reduces demand for our examination and for our platform; and loss of platform licensees reduces recurring revenue and the data and tooling on which our trading depends. Adverse developments affecting one line could therefore have a disproportionate effect on our overall results.

The market for trader identification, funding and trading technology is competitive and evolving.

We compete with other proprietary trading firms, trader-evaluation and funded-account providers and vendors of trading and risk technology, several of which have greater financial, technical and marketing resources, larger user communities and more established brands. Turnkey infrastructure providers reduce barriers to entry for competitors, and competitive pressure may compress our examination fees, licensing fees and trader-compensation economics. We may be unable to compete effectively or to sustain our pricing.

We must continuously attract examination candidates, and our acquisition costs may rise.

Because examination fees are a primary revenue line and the source of our qualified-trader pipeline, our results depend on a continuous flow of candidates. We rely on paid digital advertising, affiliates and social-media promotion, and acquisition costs may increase as channels become less effective or as advertising-platform and data-privacy rules change. A decline in candidate volume would reduce examination revenue and constrain our trading operations.

Our certification examination may not reliably predict trading performance.

Our model assumes that the examination identifies candidates likely to generate positive trading results. If the examination does not effectively predict live-market performance, traders engaged by us may underperform or generate losses, our trading results will suffer and we may incur compensation obligations disproportionate to the value generated. Past examination or trading results are not indicative of future performance.

A portion of our revenue depends on net trading results, which are inherently volatile and may be negative.

We retain net proprietary trading profit after trader compensation, and this revenue line is inherently volatile and unpredictable. Trading results may be negative in any period, and trading losses, together with fixed compensation and operating costs, could exceed our other revenue and deplete our capital. We cannot assure you that our proprietary trading will be profitable, and adverse trading results could materially harm our financial condition. No proceeds of

the Offering will be contributed to TRADEFUNDED Capital LLC as trading capital or used to fund trader accounts; all trading accounts are funded solely from operating revenue.

Trading futures involves substantial leverage, and losses may be rapid, substantial and exceed the capital committed.

Futures and related instruments are highly leveraged, and adverse price movements can produce losses that are large relative to the capital committed and that exceed initial margin. Markets may gap, become illiquid or move sharply in response to economic, geopolitical or other events. We may be required to satisfy margin calls on short notice, and a failure to manage leverage and liquidity could result in forced liquidations and significant losses.

Our risk-management systems and controls may fail to prevent significant losses.

We rely on our risk-management policies, position and loss limits and the controls embedded in our platform to constrain trading risk. These systems may fail, may be circumvented or may prove inadequate in fast-moving or unprecedented market conditions. A breakdown in risk management, including erroneous data, model error, latency or system failure, could permit positions or losses beyond our intended limits and materially harm us.

We are exposed to trader misconduct, limit breaches and rogue trading.

Because the traders we engage trade firm capital, the unauthorized, negligent or fraudulent conduct of a single trader, including breaches of trading limits, prohibited strategies, falsification of activity or collusion, could result in substantial trading losses, regulatory exposure and reputational harm. We may be unable to detect or prevent such conduct in time to avoid material loss, and our recourse against an individual trader may be limited.

We depend on futures commission merchant, clearing and execution relationships and are subject to counterparty risk.

We currently access the futures markets and trade as principal through a single established clearing relationship, and our continued market access depends on that relationship and on any additional futures commission merchant, clearing and execution relationships we may establish. These relationships may be terminated, repriced or made subject to increased margin or capital requirements on short notice, and we may be unable to obtain replacements on acceptable terms. We are also exposed to the credit and operational risk of these intermediaries, including the risk of their default or insolvency, which could impair access to our capital and positions.

We depend on identifying, engaging and retaining a sufficient number of qualified traders.

Our trading revenue depends on engaging and retaining traders capable of generating positive trading results. We may be unable to identify enough qualified candidates, and we compete for trading talent with firms offering greater compensation or resources. The loss of productive traders, or our inability to scale our trader base, would adversely affect our trading results and growth.

Our published compensation schedule creates fixed obligations that may exceed associated trading gains.

We engage qualified traders under a published compensation schedule. Depending on its terms, we may incur compensation obligations irrespective of, or in excess of, the trading results generated by a given trader or in a given period. Modifications to the schedule may give rise to disputes, claims or attrition, and our compensation costs may be difficult to align with our revenue.

The classification of our traders is uncertain and may expose us to employment-related liabilities.

The legal characterization of our traders as independent contractors or employees is uncertain and depends on facts, applicable law and evolving standards. A determination that traders are employees, or are otherwise entitled to wage, benefit, tax-withholding or similar protections, could subject us to back pay, taxes, penalties, benefit obligations and litigation, and could require changes to our model that increase our costs.

Defects, errors or outages in our platform could cause trading losses and expose us to liability.

Our proprietary trading and risk-management platform is integral to our trading and risk management and to our licensing revenue. Software defects, errors, latency, capacity constraints and outages, including those originating with third-party providers, could cause or fail to prevent trading losses, disrupt our operations, harm our licensees and expose us to claims. We may be unable to fully disclaim liability for such events notwithstanding the terms of our agreements.

Our platform licensing revenue may be concentrated among a limited number of licensees.

Our licensing revenue may depend on a limited number of licensees, and the loss of one or more significant licensees, or a reduction in their usage, could materially reduce this revenue line. Licensees may also assert claims arising from platform performance, and licensing our risk and trading technology to third parties may expose us to additional liability.

The Issuer's management may have broad discretion in how the Issuer uses the net proceeds of the Offering.

Unless the Issuer has agreed to a specific use of the proceeds from the Offering, the Issuer’s management will have considerable discretion over the use of proceeds from the Offering. You may not have the opportunity, as part of your investment decision, to assess whether the proceeds are being used appropriately.

The regulatory status of our business is uncertain and continues to evolve.

The regulatory treatment of our integrated model, administering a paid certification examination, compensating third-party traders to trade firm capital and licensing trading and risk technology, is novel and unsettled under U.S. and foreign law. Regulators, including the U.S. Commodity Futures Trading Commission, the National Futures Association, the U.S. Securities and Exchange Commission, state authorities and foreign regulators, may take positions different from ours, may adopt new rules applicable to our sector or may characterize our activities in ways that subject us to additional regulation. Any such development could require us to modify, suspend or cease aspects of our business.

We or our traders may be required to register with, or become licensed by, financial regulators.

Our access to and activity in the futures markets, and the engagement of traders to trade firm capital, may require that we or our traders obtain registrations or licenses, including registration with the National Futures Association or status as a registered introducing broker, commodity trading advisor, commodity pool operator, floor trader or associated person, as applicable. We or our traders may be unable to obtain or maintain required registrations on a timely basis or at all, and the associated compliance, capital and supervisory obligations could be significant. As a result, we may be required to restrict our activities or withdraw from affected markets.

Our examination fees or trader arrangements could be recharacterized as regulated products.

There is a risk that a regulator or court could characterize our examination fees, our compensation arrangements or our trading activity as the offer or sale of securities, the offer of commodity interests, the operation of a commodity pool or another regulated product or service. Such a characterization could subject us to registration requirements, rescission rights, civil penalties and private claims, any of which could materially harm us.

We are subject to consumer-protection and advertising laws governing our examination and earnings representations.

Our marketing of the examination and any representations regarding the likelihood of qualifying, of being engaged to trade firm capital or of earning compensation are subject to federal and state consumer-protection and advertising laws, including prohibitions on unfair or deceptive acts and practices and standards governing earnings and performance claims. Regulators or private claimants may allege that such representations are misleading, which could result in enforcement actions, fines, restitution, injunctions, mandatory changes to our practices and reputational harm.

We are subject to anti-money-laundering, sanctions and related compliance obligations.

Our collection of fees and payment of trader compensation, particularly across borders, subjects us to anti-money-laundering, know-your-customer, sanctions and related requirements. Failure to maintain adequate compliance programs could result in penalties, loss of banking or payment-processing relationships and reputational harm.

Our cross-border activities subject us to foreign regulation.

To the extent we administer the examination, engage traders or license our platform outside the United States, we are subject to the laws and regulators of those jurisdictions, several of which have increased scrutiny of our sector. We

may be required to implement geographic restrictions, modify our offerings or withdraw from jurisdictions, any of which could reduce our addressable market and revenue.

If the Issuer or any of its subsidiaries were deemed an investment company under the Investment Company Act, applicable restrictions could make it impractical for us to continue our business as contemplated.

The Investment Company Act of 1940, as amended (the “Investment Company Act”), regulates companies engaged in investing, reinvesting, owning, holding or trading in securities. Under Section 3(a)(1)(A) of the Investment Company Act, an issuer is an investment company if it is, or holds itself out as being, engaged primarily, or proposes to engage primarily, in the business of investing, reinvesting or trading in securities. Under Section 3(a)(1)(C) of the Investment Company Act, an issuer is an investment company if it is engaged, or proposes to engage, in the business of investing, reinvesting, owning, holding or trading in securities and owns or proposes to acquire investment securities having a value exceeding forty percent (40%) of the value of its total assets, exclusive of U.S. government securities and cash items, on an unconsolidated basis. Investment securities do not include U.S. government securities, cash items or securities issued by majority-owned subsidiaries that are not themselves investment companies and are not relying on the exclusions in Section 3(c)(1) or Section 3(c)(7) of the Investment Company Act.

The Issuer does not trade, does not hold any trading account or position and does not maintain the clearing relationship. All proprietary trading is conducted by TRADEFUNDED Capital. On an unconsolidated basis, the Issuer’s assets consist of cash and cash equivalents and the equity interests it holds in TRADEFUNDED Capital, of which it owns ninety-eight percent (98%), and Tachyon, which is wholly owned. Each subsidiary is a majority-owned subsidiary that the Issuer believes is not itself an investment company and does not rely on the exclusions in Section 3(c)(1) or Section 3(c)(7) of the Investment Company Act. TRADEFUNDED Capital trades exchange-listed futures contracts as principal, and futures contracts are generally not securities for purposes of the Investment Company Act. The Issuer holds itself out as operating a certification-examination, trader-engagement and technology-licensing business and does not hold itself out as being engaged primarily in the business of investing, reinvesting or trading in securities. On that basis, the Issuer does not believe that it or any of its subsidiaries is an investment company.

That conclusion depends on facts that may change and on legal standards that are subject to interpretation, and the Issuer has not sought or obtained a no-action position or other assurance from the U.S. Securities and Exchange Commission regarding its status or the status of any subsidiary under the Investment Company Act. The Issuer describes itself as a proprietary trading firm, net proprietary trading profit and loss retained after trader compensation is one of the Issuer’s three revenue lines, and a regulator or court could conclude that the Issuer holds itself out as being engaged primarily in trading. If TRADEFUNDED Capital or Tachyon acquires or holds instruments that are securities for purposes of the Investment Company Act, including shares of money market funds or other pooled vehicles, security futures products, options on securities or futures on narrow-based security indices, or if the Issuer or a subsidiary holds cash in instruments other than U.S. government securities and cash items, the Issuer or a subsidiary could exceed the forty percent (40%) threshold or otherwise come within the definition of investment company, whether or not intended.

If the Issuer or any subsidiary were determined to be an investment company required to register under the Investment Company Act, it would become subject to substantial regulation governing capital structure, use of leverage, issuance of securities and options, governance, custody of assets, recordkeeping, reporting and transactions with affiliated persons. Registered investment companies are not permitted to operate in the manner in which the Issuer operates or to maintain many of the affiliate relationships described in this Form C. If registration were required and the Issuer failed to register, the Issuer could be required to cease substantially all of its activities, could be subject to injunctive relief or monetary penalties in an action brought by the U.S. Securities and Exchange Commission, could be sued by Investors for damages caused by the violation, and any contract to which the Issuer is a party that is made in, or whose performance involves, a violation of the Investment Company Act would be unenforceable by any party unless a court determined that enforcement would produce a more equitable result than nonenforcement and would not be inconsistent with the purposes of the Investment Company Act. Compliance with the Investment Company Act, or restructuring to avoid its application, would require the Issuer to incur substantial expense, could require the Issuer to modify or discontinue one or more of its revenue lines and could have a material adverse effect on the Issuer’s business, financial condition and results of operations.

Distributions are not guaranteed, are subject to the Manager Committee’s sole discretion, and may not be made for extended periods of time.

Under Section 6.3 of the Operating Agreement, distributions of Distributable Cash shall be made to Members when determined by the Manager Committee in its absolute and sole discretion. There is no guarantee that the Company will generate sufficient Distributable Cash to make distributions to Members, or that the Manager Committee will elect to make distributions even if Distributable Cash is available. Past distributions, if any, are not indicative of future distributions. You may receive no distributions on your investment for extended periods or at all.

Five percent (5%) of the Issuer’s Pre-Distribution Cash is allocated to TRADEFUNDED Capital or another affiliate before any distributions are made to Members.

Under Section 10.1 of the Operating Agreement, five percent (5%) of the Issuer’s Pre-Distribution Cash is allocated, before any Distributable Cash is distributed to Members, for payment, contribution or other transfer to TRADEFUNDED Capital LLC or such other subsidiary or affiliate as the Manager Committee may approve, for use in connection with such entity’s operations, trading activities, working capital and trader-incentive, performance-bonus, funded-trader and similar arrangements administered outside of the Issuer. The Manager Committee has sole discretion over the timing, amount, form, characterization and recipient of transfers under this allocation and may retain unpaid amounts as reserves or working capital. This allocation reduces the cash available for distribution to Members in each period in which distributions are made, and Members have no right to direct, audit or receive amounts transferred under the allocation or to assert claims against the recipient entity.

This allocation is a contractual incentive arrangement administered by the Manager Committee and is not an equity or membership interest in the TRADEFUNDED Capital LLC. Amounts paid may be deductible by TRADEFUNDED Capital LLC to the extent permitted under applicable tax law. The timing and amount of any deduction, and the applicable reporting or withholding obligations, will depend on the facts and circumstances of the payments and the classification of the recipients.

The Units held by three of the four Founding Members are wholly unvested until a Liquidity Event, and the vesting structure may not effectively retain or incentivize management and creates tax uncertainty for the Founding Members.

Under the Operating Agreement, one hundred percent (100%) of the Units held by TraderSumo LLC, Natural Workflow LLC and Bethlem Royal Holdings LLC remains unvested unless and until a Liquidity Event occurs and is forfeited only if the applicable Vesting Member or its principal service provider voluntarily departs or is terminated for Cause before a Liquidity Event. Because vesting occurs on an all-or-nothing basis solely upon a Liquidity Event, the structure provides no time-based retention incentive, and a Vesting Member whose service ends by reason of death, disability, removal without Cause or constructive termination retains all of its Units, together with full distribution, allocation and voting rights, notwithstanding that it no longer provides services to the Issuer. Unvested Units also carry full distribution, allocation and voting rights before a Liquidity Event, and the Units held by Oasis Holdings, Ltd., LLC are fully vested and not subject to forfeiture. As a result, the Issuer may be required to share its economics and governance with holders who no longer contribute services, and the intended incentive effects of the vestingstructuremaynotberealized.

The vesting structure may result in taxable income to certain Founding Members. Certain Founding Members received Units for no cash consideration that remain subject to forfeiture until a Liquidity Event. If the Units constitute property transferred in connection with the performance of services and no timely election under Section 83(b) of the Internal Revenue Code applies, a Founding Member may recognize ordinary compensation income when the Units become substantially vested upon a Liquidity Event, generally based on the fair market value of the Units at that time. Because a Liquidity Event could occur when the Units have substantial value, the resulting tax liability could be material. The Issuer makes no representation regarding the tax treatment of the Founding Members' Units, and each Founding Member should consult its own tax advisor regarding the application of Section 83 to its Units.

Control of the Issuer is concentrated in the Founding Members; the Managers are entities acting through designated representatives, and one Manager may be removed only for Cause.

The Founding Members hold Units representing sixty-five percent (65%) of the Issuer’s fully diluted Percentage Interests, constituting a substantial majority of the issued Units outstanding as of the date of this Form C, and the Issuer is managed exclusively by a Manager Committee comprised of three entity Managers, each acting through a designated natural-person Manager Representative. A Manager may replace its Manager Representative at any time upon notice, and Investors will have no ability to approve any replacement. In addition, Oasis Holdings, Ltd., LLC may be removed as a Manager only for Cause, and removal of any Manager requires the affirmative vote of the other two Managers together with Members holding a majority-in-interest of the issued Units. These provisions entrench existing management, and Investors purchasing Securities in this Offering will be unable to influence the appointment, removal or replacement of any Manager or Manager Representative.

The Manager Committee’s approval requirements could result in deadlock or delay.

The Manager Committee consists of three Managers; ordinary decisions require the approval of at least two Managers, and Reserved Matters, including securities issuances in excess of authorized amounts, indebtedness or guarantees in excess of five thousand dollars ($5,000), affiliate transactions, amendments to the Operating Agreement, mergers,

dissolution and material tax elections, require the approval of all Managers then serving. If a vacancy reduces the Manager Committee to two Managers, all actions require the approval of both. The Operating Agreement contains no deadlock-resolution mechanism, and a disagreement among the Managers, or a prolonged vacancy, could delay or prevent the Issuer from taking actions material to its business, including financings, distributions, hiring decisions and strategic transactions.

The Issuer may accept Capital Contributions in U.S. dollar-denominated stablecoins.

The Operating Agreement permits Capital Contributions to be made in USD Coin (USDC) or other U.S. dollar-denominated stablecoins approved by the Manager Committee, valued at one U.S. dollar ($1.00) per unit at the time of transfer. Stablecoins may deviate from their intended one-dollar value, and the issuer of a stablecoin, or the reserves backing it, may fail, be frozen or become subject to regulatory action. Holding, transferring and converting digital assets exposes the Issuer to custody, cybersecurity, counterparty, banking-access and evolving regulatory risks, and any loss in value of digital assets accepted as Capital Contributions would be borne by the Issuer and would not be recoverable from the contributing Member.

The Company is subject to U.S. federal income tax at the entity level, and distributions to you may be taxed a second time.

On July 2, 2026, the Company filed with the Internal Revenue Service an election on Form 8832 to be classified as an association taxable as a corporation for U.S. federal income tax purposes. The Company will pay U.S. federal income tax on its taxable income at the corporate rate, and any distributions the Manager Committee elects to make out of the Company’s current or accumulated earnings and profits will be taxable to you as dividend income. The same earnings may therefore be taxed twice, once to the Company and again to you. The election reduces the cash available for distribution and for the Company’s operations relative to the treatment that applied before the election.

Our indemnification and expense-advancement obligations could require us to expend substantial resources.

Under Section 15.1 of the Operating Agreement, the Issuer is required, to the fullest extent permitted by law, to indemnify, defend and hold harmless each Manager, Manager Representative and Member, together with their respective related persons, from claims arising out of or incidental to any act or omission in connection with the Issuer’s business, other than willful misconduct, fraud or knowing violations of law, and to advance defense expenses before any final determination of entitlement, subject to an undertaking to repay. These obligations could require the Issuer to expend substantial amounts, including on behalf of persons ultimately found not to be entitled to indemnification but unable to repay advanced amounts, which could reduce the cash available for operations and distributions to Members.

The Consent Order against our Co-Founder and Chief Technology Officer could adversely affect our regulatory standing, our business relationships and our reputation.

As described under “The CFTC Action and Consent Order,” Ryan Masten, our Co-Founder and Chief Technology Officer, and BareIt Media LLC, a company he owns and controls, are subject to a 2023 federal court consent order resolving CFTC claims that BareIt Media acted as an unregistered commodity trading advisor and that Mr. Masten acted as an unregistered associated person of a commodity trading advisor in connection with the SignalPush service. The Consent Order remains in effect, and its terms, other than the civil monetary penalty, are enforceable through contempt proceedings.

Neither the Company nor any subsidiary is a party to the Consent Order, and the injunction is limited to the specific unregistered activity it describes. By its terms, and consistent with Rule 65 of the Federal Rules of Civil Procedure, the injunctive provisions bind the defendants, their officers, agents, servants, employees and attorneys, and other persons in active concert or participation with them who receive actual notice of the order. The Consent Order nonetheless presents risks to the Company. The findings and conclusions in the Consent Order may be given preclusive effect in a statutory disqualification proceeding or certain other proceedings brought by the CFTC. If the Company or an affiliate were in the future required, or elected, to register with the CFTC or to become a member of the National Futures Association, Mr. Masten’s role as an officer and indirect owner could subject the application to heightened scrutiny, conditions, delay or denial, which could require changes to our management or ownership structure or limit our ability to pursue activities requiring registration. Futures commission merchants, clearing firms, banks, payment processors, insurers and other counterparties may consider the Consent Order in their diligence and could decline to establish or maintain relationships with us, impose additional conditions or increase our costs. Publicity concerning the Consent Order could also harm our reputation with trader candidates, funded traders, counterparties and investors, as described in the general reputation risk factor. If Mr. Masten were found to have violated the injunction, or if the Company or its personnel were found to have acted in active concert or participation with a violation after receiving actual notice of the Consent Order, the Company could face contempt proceedings, additional regulatory scrutiny, management disruption and reputational harm. Any of the foregoing could materially and adversely affect our business, results of operations and the value of the Units.

Risks Related to the Offering

If the Issuer were an investment company, the Issuer would not have been eligible to conduct this Offering and Investors could have rescission rights.

Regulation Crowdfunding makes the exemption provided by Section 4(a)(6) of the Securities Act unavailable to an issuer that is an investment company, as defined in Section 3 of the Investment Company Act, or that is excluded from the definition of investment company by Section 3(b) or Section 3(c) of the Investment Company Act. The Issuer’s position is that it falls outside the definition of investment company in Section 3(a) of the Investment Company Act and that it does not rely on the exclusions in Section 3(b) or Section 3(c) of the Investment Company Act. If it were later determined that the Issuer is an investment company, the Issuer would not have been eligible to offer or sell the Securities in reliance on Section 4(a)(6) of the Securities Act. In that event, each Investor could have the right to rescind its purchase and recover the purchase price paid, plus interest, subject to applicable limitations periods. The Issuer does not expect that it would have sufficient funds to satisfy rescission claims. The Issuer could also be subject to enforcement action by the U.S. Securities and Exchange Commission or state securities regulators, could be required to return the proceeds of this Offering, could become ineligible to conduct future offerings in reliance on Section 4(a)(6) of the Securities Act and could incur substantial costs in defending any such claim or action, any of which could have a material adverse effect on the Issuer and on the value of the Securities.

State and federal securities laws are complex, and the Issuer could potentially be found to have not complied with all relevant state and federal securities law in prior offerings of securities.

The Issuer has conducted previous offerings of securities and may not have complied with all relevant state and federal securities laws. If a court or regulatory body with the required jurisdiction ever concluded that the Issuer may have violated state or federal securities laws, any such violation could result in the Issuer being required to offer rescission rights to investors in such offering. If such investors exercised their rescission rights, the Issuer would have to pay to such investors an amount of funds equal to the purchase price paid by such investors plus interest from the date of any such purchase. No assurances can be given the Issuer will, if it is required to offer such investors a rescission right, have sufficient funds to pay the prior investors the amounts required or that proceeds from this Offering would not be used to pay such amounts.

In addition, if the Issuer violated federal or state securities laws in connection with a prior offering and/or sale of its securities, federal or state regulators could bring an enforcement, regulatory and/or other legal action against the Issuer which, among other things, could result in the Issuer having to pay substantial fines and be prohibited from selling securities in the future.

The U.S. Securities and Exchange Commission does not pass upon the merits of the Securities or the terms of the Offering, nor does it pass upon the accuracy or completeness of any Offering document or literature.

You should not rely on the fact that our Form C is accessible through the U.S. Securities and Exchange Commission’s EDGAR filing system as an approval, endorsement or guarantee of compliance as it relates to this Offering. The U.S. Securities and Exchange Commission has not reviewed this Form C, nor any document or literature related to this Offering.

Neither the Offering nor the Securities have been registered under federal or state securities laws.

No governmental agency has reviewed or passed upon this Offering or the Securities. Neither the Offering nor the Securities have been registered under federal or state securities laws. Investors will not receive any of the benefits available in registered offerings, which may include access to quarterly and annual financial statements that have been audited by an independent accounting firm. Investors must therefore assess the adequacy of disclosure and the fairness of the terms of this Offering based on the information provided in this Form C and the accompanying exhibits.

The Intermediary Fees paid by the Issuer are subject to change depending on the success of the Offering.

At the conclusion of the Offering, the Issuer shall pay the Intermediary a cash fee equal to the greater of (A) $15,000.00 or (B) the amount determined pursuant to the following schedule: (1) zero percent (0%) of any amounts raised up to

$100,000.00, and (2) six percent (6%) of any amounts raised exceeding $100,000.01 but not exceeding $5,000,000.00. The Issuer has paid the Intermediary a non-refundable fee of fifteen thousand dollars ($15,000.00) related to certain onboarding expenses. The compensation paid by the Issuer to the Intermediary may impact how the Issuer uses the net proceeds of the Offering.

The Issuer has the right to limit individual Investor commitment amounts based on the Issuer’s determination of an Investor’s sophistication.

The Issuer may prevent any Investor from committing more than a certain amount in this Offering based on the Issuer’s determination of the Investor’s sophistication and ability to assume the risk of the investment. This means that your desired investment amount may be limited or lowered based solely on the Issuer’s determination and not in line with relevant investment limits set forth by the Regulation CF rules. This also means that other Investors may receive larger allocations of the Offering based solely on the Issuer’s determination.

The Issuer has the right to extend the Offering Deadline.

The Issuer may extend the Offering Deadline beyond what is currently stated herein. This means that your investment may continue to be held in escrow while the Issuer attempts to raise the Target Offering Amount even after the Offering Deadline stated herein is reached. While you have the right to cancel your investment in the event the Issuer extends the Offering Deadline, if you choose to reconfirm your investment, your investment will not be accruing interest during this time and will simply be held until such time as the new Offering Deadline is reached without the Issuer receiving the Target Offering Amount, at which time it will be returned to you without interest or deduction, or the Issuer receives the Target Offering Amount, at which time it will be released to the Issuer to be used as set forth herein. Upon or shortly after the release of such funds to the Issuer, the Securities will be issued and distributed to you.

The Issuer may also end the Offering early.

If the Target Offering Amount is met after 21 calendar days, but before the Offering Deadline, the Issuer can end the Offering by providing notice to Investors at least 5 business days prior to the end of the Offering. This means your failure to participate in the Offering in a timely manner, may prevent you from being able to invest in this Offering – it also means the Issuer may limit the amount of capital it can raise during the Offering by ending the Offering early.

The Issuer has the right to conduct multiple closings during the Offering.

If the Issuer meets certain terms and conditions, an intermediate close (also known as a rolling close) of the Offering can occur, which will allow the Issuer to draw down on seventy percent (70%) of Investor proceeds committed and captured in the Offering during the relevant period. The Issuer may choose to continue the Offering thereafter. Investors should be mindful that this means they can make multiple investment commitments in the Offering, which may be subject to different cancellation rights. For example, if an intermediate close occurs and later a material change occurs as the Offering continues, Investors whose investment commitments were previously closed upon will not have the right to re-confirm their investment as it will be deemed to have been completed prior to the material change.

Risks Related to the Securities

Investors will have no control over the management or operations of the Company and will be minority investors with limited voting rights.

The Company is managed by the Manager Committee, and under Section 3.4 of the Operating Agreement, Members have no right to participate in the management of the Company’s affairs. All operational and strategic decisions, including decisions regarding distributions, admission of new members, and administration of the TRADEFUNDED Capital Funding Allocation, are made by the Manager Committee in its sole discretion. As a minority investor, your Units, when combined with other investors in this Offering, is unlikely to constitute a majority in interest sufficient to a remove or appoint Managers. You should not invest unless you are comfortable relying entirely on the Company’s management team.

Your Units purchased in this Offering may be further diluted in the future without your consent.

The issuance of Units in the Offering will dilute the Units of existing Members. Section 6.3 of the Operating Agreement permits the Manager Committee to issue additional Units, and Section 16.2 permits the Manager Committee to amend Exhibit A of such Operating Agreement without consent of or notice to the Members. There is no limit on the number of Units that the Company may issue or the number of Members that may be admitted. There can be no assurance that additional Units will not be issued in the future at prices above, below, or equal to the offering price, which would further dilute your interest in the Company.

The Securities being offered will be subject to dilution. The Company may issue additional interests to raise capital, compensate service providers, satisfy obligations, or for other purposes determined by the Managers, without your consent, and as a consequence holders of Securities will be subject to dilution in an unpredictable amount. Such dilution will reduce an Investor’s control and economic interests in the Issuer. The amount of additional financing needed by Issuer will depend upon several contingencies not foreseen at the time of this offering. Each such round of financing (whether from the Issuer or other investors) is typically intended to provide the Issuer with enough capital to reach the next major corporate milestone. If the funds are not sufficient, Issuer may have to raise additional capital at a price unfavorable to the existing investors, including the purchaser. The availability of capital is at least partially a function of capital market conditions that are beyond the control of the Issuer. There can be no assurance that the Issuer will be able to predict accurately the future capital requirements necessary for success or that additional funds will be available from any source. Failure to obtain such financing on favorable terms could dilute or otherwise severely impair the value of the purchaser’s Securities.

You will not be allocated, and will not be able to use, any of the Company’s losses.

Following the effective date of the election, items of the Company’s income, gain, loss, deduction and credit are taken into account solely by the Company and are not allocated to Members. Any net operating losses the Company generates will remain at the Company level, will be usable only against the Company’s own future taxable income subject to the limitations of Sections 172 and 382 of the Internal Revenue Code, and will not be available to offset your other income. The Company has incurred net losses since inception and may never generate taxable income against which those losses can be applied.

The Company may owe corporate income tax on income it has not received in cash and the mark-to-market accounting method used by TRADEFUNDED Capital LLC may accelerate and increase that risk.

To the extent TRADEFUNDED Capital LLC is treated as a partnership for U.S. federal income tax purposes, the Company’s share of its net trading profit will be included in the Company’s taxable income when earned, whether or not TRADEFUNDED Capital LLC distributes cash to the Company. The Manager Committee controls distributions from TRADEFUNDED Capital LLC and has no obligation to cause distributions sufficient to fund the Company’s tax liabilities. A shortfall would require the Company to fund taxes from working capital, including proceeds of this Offering, which would reduce the amounts available for the uses described under the section titled “Use of Proceeds.”

TRADEFUNDED Capital LLC has elected to apply the mark-to-market method of accounting under Section 475(f)

of the Internal Revenue Code to certain trading activities. Under this method, applicable open trading positions are treated as sold at fair market value at the end of each taxable year, which may result in taxable income even though the positions have not been closed and no corresponding cash has been realized.

Because the Company owns 98% of TRADEFUNDED Capital, the Company generally must include its distributive share of TRADEFUNDED Capital's taxable income, including income resulting from its Section 475(f) mark-to-market election, whether or not TradeFunded Capital distributes sufficient cash to fund the Company's resulting tax liability. Accordingly, the Company may be required to use other available cash or working capital to satisfy its corporate income tax obligations, which could reduce cash available for operations or distributions to Members.

Our election to be taxed as a corporation has been filed with the Internal Revenue Service but has not been accepted, and we can give no assurance that it will be accepted.

The Company filed the election on July 2, 2026 and requested that it be effective as of February 10, 2026, the Company’s date of formation. Because the election was filed more than 75 days after that date, the Company also requested late classification relief under Revenue Procedure 2009-41. Relief under Revenue Procedure 2009-41 is not self-executing. The Internal Revenue Service determines whether the requirements for relief have been satisfied and notifies the entity of the result of its determination, and the Company has not received that notice as of the date of this Form C. The Company can give no assurance that relief will be granted, that the Internal Revenue Service will accept the election as filed, or that the Internal Revenue Service will agree with the Company’s determination of its classification for U.S. federal income tax purposes. The Company prepares its financial statements and conducts its tax reporting on the basis of its own determination of its classification, without confirmation from the Internal Revenue Service.

If our election is not accepted as requested, our tax reporting and our financial statements may require revision.

If relief under Revenue Procedure 2009-41 is not granted, the election will instead be effective on the date 75 days before the date on which it was filed. In that event the Company will have been classified as a partnership for a short period beginning on February 10, 2026, the Company will be treated as having contributed all of its assets and liabilities to a newly formed corporation in exchange for stock and then liquidated, and the Members during that short period will receive Schedules K-1 for that period. If the Internal Revenue Service were to determine that the election is not valid, the Company would continue to be classified as a partnership until a valid election is made, and the tax consequences of an investment in the Securities would differ materially from those described in this Form C. Any of these outcomes could require the Company to revise its tax returns, its tax reporting to Members and Investors and its financial statements, could result in additional tax, interest and penalties, and could affect the Company’s ability to change its classification in the future. You should consult your own tax advisor and should not invest in reliance on any particular tax classification of the Company.

You will not receive a Schedule K-1, and the Securities may not qualify as qualified small business stock.

The Company will report distributions, if any, on Internal Revenue Service Form 1099-DIV rather than on Schedule K-1, and no Investor purchasing Units in this Offering will receive a Schedule K-1 with respect to the Units. Whether Units constitute stock of a qualified small business for purposes of Section 1202 of the Internal Revenue Code is unsettled, and the Company makes no representation that any Investor will be eligible for the gain exclusion under Section 1202 or for any other benefit available to holders of qualified small business stock. You should not invest in reliance on any such treatment.

Investors admitted as new Members are subject to all restrictions and obligations of the Operating Agreement, which was negotiated without your participation.

Each investor who purchases Securities in the Offering will be admitted as a Member of the Company (or will hold a beneficial interest through a custodial or nominee arrangement) and will be bound by all of the terms and conditions of the Operating Agreement. The Operating Agreement was negotiated among the original Members and may contain provisions that are less favorable to new Members than the terms that might be negotiated in an arm’s-length transaction with a new investor. These provisions include, but are not limited to transfer restrictions requiring Majority Manager Approval (Section 12.1); the prohibition on participation in management (Section 3.4); the limitation of Manager liability to willful misconduct, fraud, or knowing violation of the law (Section 15.2); and the Manager Committee’s unilateral authority to issue additional Units (Section 6.3) and amend Exhibit A (Section 16.2). You should carefully review the Operating Agreement before investing.

Investors in this offering will sign our Subscription Agreement which contains a voting proxy and will have no influence on the Issuer’s decisions.

In order to invest in this Offering, Investors are required to execute a Subscription Agreement pursuant to which they grant an irrevocable proxy and power of attorney with respect to voting and consent rights. As a result, Investors will not have the ability to vote directly on matters affecting the Issuer or to participate in management decisions.

Because Investors do not control the voting of the Securities, they will have no practical ability to influence the election of managers, approval of significant transactions, amendments to the Issuer’s governing documents, or other matters requiring member approval, and must rely entirely on the discretion and judgment of the Issuer’s management in operating the business and making strategic decisions. The interests of management and other members may not always align with the interests of Investors.

The Securities will not be freely tradable under the Securities Act until one year from when the securities are issued. Although the Securities may be tradable under federal securities law, state securities regulations may apply, and each Investor should consult with their attorney.

You should be aware of the long-term nature of this investment. There is not now and likely will not ever be a public market for the Securities. Because the Securities have not been registered under the Securities Act or under the securities laws of any state or foreign jurisdiction, the Securities have transfer restrictions and cannot be resold in the United States except pursuant to Rule 501 of Regulation CF. It is not currently contemplated that registration under the Securities Act or other securities laws will be effected. Limitations on the transfer of the Securities may also adversely affect the price that you might be able to obtain for the Securities in a private sale. Investors should be aware of the long-term nature of their investment in the Issuer. Each Investor in this Offering will be required to represent

that they are purchasing the Securities for their own account, for investment purposes and not with a view to resale or distribution thereof. If a transfer, resale, assignment or distribution of the Security should occur, if the Security is still held by the original purchaser directly, the transferee, purchaser, assignee or distribute, as relevant, will be required to sign a new Omnibus Nominee Trust Agreement (attached as Exhibit D). Additionally, Investors will only have a beneficial interest in the Securities, not legal ownership, which may make their resale more difficult as it will require coordination with the Custodian.

Investors will not be entitled to any inspection or information rights other than those required by law.

Investors will not have the right to inspect the books and records of the Issuer or to receive financial or other information from the Issuer, other than as required by law. Other security holders of the Issuer may have such rights. Regulation CF requires only the provision of an annual report on Form C and no additional information. Additionally, there are numerous methods by which the Issuer can terminate annual report obligations, resulting in no information rights, contractual, statutory or otherwise, owed to Investors. This lack of information could put Investors at a disadvantage in general and with respect to other security holders, including certain security holders who have rights to periodic financial statements and updates from the Issuer such as quarterly unaudited financials, annual projections and budgets, and monthly progress reports, among other things.

There is no present market for the Securities and we have arbitrarily set the price.

The offering price was not established in a competitive market. We have arbitrarily set the price of the Securities with reference to the general status of the securities market and other relevant factors. The offering price for the Securities should not be considered an indication of the actual value of the Securities and is not based on our asset value, net worth, revenues or other established criteria of value. We cannot guarantee that the Securities can be resold at the offering price or at any other price.

Each Investor must purchase the Securities in the Offering for Investor’s own account for investment.

Each Investor must purchase the Securities for its own account for investment, not as a nominee or agent, and not with a view to, or for resale in connection with, the distribution thereof, and each Investor must represent it has no present intention of selling, granting any participation in, or otherwise distributing the same. Each Investor must acknowledge and agree that the Subscription Agreement and the underlying securities have not been, and will not be, registered under the Securities Act or any state securities laws, by reason of specific exemptions under the provisions thereof which depend upon, among other things, the bona fide nature of the investment intent and the accuracy of the Investor representations.

Investors purchasing the Securities in this Offering may be significantly diluted as a consequence of subsequent financings.

The Securities being offered will be subject to dilution. The Issuer may issue additional equity to employees, management, third-party financing sources and potential strategic partners in amounts that are uncertain at this time, and as a consequence holders of Securities will be subject to dilution in an unpredictable amount. Such dilution will reduce an Investor’s economic interests in the Issuer. The amount of additional financing that may be needed by Issuer will depend upon several contingencies not foreseen at the time of this offering. Each such round of financing (whether from the Issuer or other investors) is typically intended to provide the Issuer with enough capital to reach the next major corporate milestone. If the funds are not sufficient, Issuer may have to raise additional capital at a price unfavorable to the existing investors, including the purchaser. The availability of capital is at least partially a function of capital market conditions that are beyond the control of the Issuer. There can be no assurance that the Issuer will be able to predict accurately the future capital requirements necessary for success or that additional funds will be available from any source. Failure to obtain such financing on favorable terms could dilute or otherwise severely impair the value of the purchaser’s Issuer securities.

There is no guarantee of a return on an Investor’s investment.

There is no assurance that an Investor will realize a return on their investment or that they will not lose their entire investment. For this reason, each Investor should read this Form C and all exhibits carefully and should consult with their attorney and business advisor prior to making any investment decision.

Show all Risks

Discussion

Ask questions and share feedback with the TRADEFUNDED LLC team below. If you have support related questions for Republic, please contact investors@republic.co.
Loading
Logo of TRADEFUNDED LLC

TRADEFUNDED LLC

Invest in TRADEFUNDED LLC
Republic

Giving everyone access to early-stage startup investing

For investors
  • Why invest
  • How it works
  • FAQ
  • Risks
  • Privacy policy
  • Accessibility
  • Cookie Preferences
  • Form CRS
For startups
  • Why raise
  • Learn
  • FAQ
  • Tokenized assets
Company
  • About
  • Insights
  • Events
  • Contact
  • Security
  • We're hiring!
Dollar Refer a startup, get $2,500

Invest in the app

Android app iOS app

Invest in the app

Android app iOS app

This site (the "Site") is owned and maintained by OpenDeal Inc., which is not a registered broker-dealer. OpenDeal Inc. does not give investment advice, endorsement, analysis or recommendations with respect to any securities. All securities listed here are being offered by, and all information included on this Site is the responsibility of, the applicable issuer of such securities. The intermediary facilitating the offering will be identified in such offering’s documentation.

All related securities activity is conducted by OpenDeal Broker LLC a registered broker-dealer, Member of FINRA and SiPC, an affiliate of OpenDeal Inc. and OpenDeal Portal LLC, located at 149 5th Avenue, 10th Floor, New York, NY 10010. Please check our background on FINRA’s BrokerCheck.

Certain pages discussing the mechanics and providing educational materials regarding regulation crowdfunding offerings may refer to OpenDeal Broker LLC and OpenDeal Portal LLC collectively as “Republic”, solely for explanatory purposes.

Neither OpenDeal Inc., OpenDeal Portal LLC nor OpenDeal Broker LLC make investment recommendations and no communication, through this Site, or in any other medium, should be construed as a recommendation for any security offered on or off this investment platform. Investment opportunities posted on this Site are private placements of securities that are not publicly traded, involve a high degree of risk, may lose value including the total loss of invested capital, are subject to holding period requirements and are intended for investors who do not need a liquid investment. Past performance is not indicative of future results. Investors must be able to afford the loss of their entire investment. Only qualified investors, who understand the risks of early-stage investment and who meet the Republic's investment criteria may invest. Investors may be restricted to only Accredited Investors or non-U.S. persons, to invest in offerings hosted by OpenDeal Broker. Neither OpenDeal Inc., OpenDeal Portal LLC nor OpenDeal Broker LLC, nor any of their officers, directors, agents and employees make any warranty, express or implied, of any kind whatsoever related to the adequacy, accuracy or completeness of any information on this Site or the use of information on this site. Offers to sell securities can only be made through official offering documents that contain important information about the investment and the issuers, including risks. Investors should carefully read the offering documents. Investors should conduct their own due diligence and are encouraged to consult with their tax, legal and financial advisors.

By accessing the Site and any pages thereof, you agree to be bound by the Terms of Use and Privacy Policy. Please also see OpenDeal Broker’s Business Continuity Plan and Additional Risk Disclosures. All issuers offering securities under regulation crowdfunding as hosted by OpenDeal Portal LLC are listed on the All Companies Page. The inclusion or exclusion of an issuer on the Platform Page and/or Republic’s Homepage, which includes offerings conducted under regulation crowdfunding as well as other exemptions from registration, is not based upon any endorsement or recommendation by OpenDeal Inc, OpenDeal Portal LLC, or OpenDeal Broker LLC, nor any of their affiliates, officers, directors, agents, and employees. Rather, issuers of securities may, in their sole discretion, opt-out of being listed on the Platform Page and Homepage.

Investors should verify any issuer information they consider important before making an investment.

Investments in private companies are particularly risky and may result in total loss of invested capital. Past performance of a security or a company does not guarantee future results or returns. Only investors who understand the risks of early stage investment and who meet the Republic's investment criteria may invest.

Neither OpenDeal Inc., OpenDeal Portal LLC nor OpenDeal Broker LLC verify information provided by companies on this Site and makes no assurance as to the completeness or accuracy of any such information. Additional information about companies fundraising on the Site can be found by searching the EDGAR database, or the offering documentation located on the Site when the offering does not require an EDGAR filing.

To help the government fight the funding of terrorism and money laundering activities, Federal law requires all financial institutions to obtain, verify, and record information that identifies each person who opens an account. Therefore, when you use the Services we will ask for your name, address, date of birth, and other information that will allow us to identify you. We may also ask to see your driver's license, passport or other identifying documents.

Republic and its affiliates are not and do not operate or act as a bank. Certain banking services are provided by BitGo Trust Company, a South Dakota-chartered trust company and registered money services business. BitGo Trust Company is not an FDIC member. Digital (crypto) assets and investment products are not insured by the FDIC, may lose value, and are not deposits or other obligations of BitGo Trust Company and are not guaranteed by BitGo Trust Company. Terms and conditions apply.

Invest in startups using your credit card
You can invest using your credit card

Made in SF/NYC